Can Someone Sell a House if Your Name is on the Deed?

You’re wondering if someone can sell a house if your name is on the deed.  Maybe you’re worried someone is trying to cash in on a property you own a piece of without your knowledge.  Maybe you want someone else to sell a house on your behalf without you being an active participant in the transaction.  Whatever the case may be for your particular situation, we break down the ins and outs of the question of can someone sell a house if your name is on the deed.

Picture this: You’re at a family barbecue, and amidst the chatter about Uncle Joe’s latest fishing trip and Aunt Betty’s new recipe, someone drops the bombshell. “Did you hear? Cousin Bob is trying to sell Grandma’s old house. Can he even do that? I mean, my name is on the deed too!” You freeze, burger halfway to your mouth, and suddenly your Saturday afternoon gets a lot more complicated. If this scenario feels familiar, you’re not alone. Many people find themselves in a tangled web of property co-ownership, unsure of their rights and how to navigate the sale of a co-owned property.

So, can someone sell a house if your name is on the deed? The short answer: It’s complicated. The long answer: Let’s dive in and untangle this mess together. Grab a snack, get comfortable, and let’s explore the nuances of property co-ownership and the implications of having your name on a deed.

family members discussing property ownership and selling

Understanding Property Deeds and Ownership

Before we unravel the complexities of inheriting and then selling a co-owned property, let’s take a quick detour into the world of property deeds and ownership. Think of the deed as your golden ticket, proving you’re one of the lucky owners of the house in question. But it’s not just a simple “I own it, you own it” situation—there are different types of deeds and ownership that come with their own sets of rules and responsibilities.

What Is a Property Deed?

A property deed is a legal document that transfers ownership of real estate from one person (or entity) to another. It’s like the birth certificate of your property, stating who owns it and outlining any restrictions or conditions on its use.

Types of Property Ownership

Property ownership isn’t a one-size-fits-all kind of deal. Here’s a quick rundown of the most common types of ownership you might encounter:

  • Sole Ownership: This is the simplest form of ownership, where one person holds the title to the property. Think of it as flying solo in your real estate adventure.
  • Joint Tenancy: In this arrangement, two or more people own the property together, with equal shares. One of the key features of joint tenancy is the right of survivorship, meaning if one owner dies, their share automatically goes to the surviving owners.
  • Tenants in Common: This type of ownership allows multiple people to own a property together, but unlike joint tenancy, their shares can be unequal, and there’s no right of survivorship. Each owner can sell or transfer their share independently.
  • Tenancy by the Entirety: Reserved for married couples, this type of ownership treats the spouses as a single entity. It comes with survivorship rights, meaning if one spouse dies, the other automatically inherits the entire property. 

Legal Implications of Having Your Name on the Deed

Alright, now that we’ve got a handle on the basics, let’s dig into the nitty-gritty: What does it mean to have your name on the deed? Spoiler alert: It’s more than just a fancy piece of paper with your name on it.

Rights and Responsibilities of Co-Owners

When you’re a co-owner, you have certain rights and responsibilities that come with the territory. These might include:

  • Right to Use and Enjoy the Property: As a co-owner, you have the right to use and enjoy the property, whether it’s for living, renting, or good old-fashioned gardening.
  • Responsibility to Maintain and Pay for the Property: You’re also on the hook for maintaining the property and contributing to expenses like taxes, mortgage payments, and repairs.

Title vs. Deed: What’s the Difference?

Here’s where things get a bit technical: The deed is the document that transfers ownership, while the title refers to your legal ownership rights. In other words, the deed is the evidence, and the title is the actual ownership.

Need for Co-Owner Agreement to Sell

If you’re thinking about selling the property, hold your horses! You’ll need the agreement of all co-owners before you can put that “For Sale” sign in the yard. Selling a co-owned property isn’t like selling your old bike on Craigslist—it requires a bit more coordination and legal wrangling.

Types of Co-Ownership and Their Impact on Selling Property

Now that we’ve covered the basics, let’s dive into the different types of co-ownership and how they impact your ability to sell the property. Spoiler: It’s not always a smooth ride.

Joint Tenancy

  • Characteristics: Joint tenancy involves equal ownership shares among co-owners and includes the right of survivorship.
  • Right of Survivorship: This means if one co-owner passes away, their share automatically transfers to the surviving co-owners, bypassing the will and probate process.
  • Selling Implications: To sell a property held in joint tenancy, all co-owners must agree. If you’re all on the same page, great! If not, you might need to explore other legal avenues, which we’ll get into later.

Tenants in Common

  • Characteristics: This form of co-ownership allows for unequal ownership shares and does not include survivorship rights. Each owner can pass their share on to their heirs.
  • Individual Ownership Percentages: Each owner’s percentage of ownership is specified in the deed, and they can sell or transfer their share independently.
  • Selling Implications: While you can sell your share without the consent of the other co-owners, selling the entire property requires the agreement of all parties involved. Otherwise, you’re stuck with your piece of the pie.

Tenancy by the Entirety

  • Characteristics: Exclusively for married couples, this form of ownership treats the spouses as a single entity with survivorship rights.
  • Applicable to Married Couples: Only married couples can hold property as tenants by the entirety, and both must agree to sell the property.
  • Selling Implications: Selling a property under tenancy by the entirety requires the consent of both spouses. If you’re not on the same page, you might need to consult a marriage counselor—or a lawyer.
deed of a house owned by more than one owner

Common Scenarios and Challenges in Selling a Co-Owned Property

So, you’ve got a handle on the different types of co-ownership. But what happens when the rubber meets the road, and you actually want to sell the property? Here are some common scenarios and the challenges you might face.

All Co-Owners Agree to Sell

In an ideal world, everyone is on the same page, and selling the property is a straightforward process. You’ll need to agree on a price, hire a real estate agent, and navigate the sale just like any other property.

One Co-Owner Wants to Sell, Others Do Not

Uh-oh. This is where things can get sticky. If one co-owner wants to sell, but the others are digging in their heels, you have a few options:

  • Partition Action: This legal action can force the sale of the property or divide it among the co-owners. It’s a bit like a real estate divorce—messy, but sometimes necessary.
  • Mediation: Before you head to court, consider mediation. A neutral third party can help facilitate a discussion and hopefully reach a mutually agreeable solution.

Disputes Among Co-Owners

Disputes among co-owners can arise for various reasons, from disagreements over the sale price to who’s responsible for repairs. Legal remedies include:

  • Negotiation: Try to hash out your differences directly. It might save you time, money, and a lot of headaches.
  • Mediation or Arbitration: These are less formal than court proceedings and can provide a quicker resolution.
  • Court Action: If all else fails, you might need to take the matter to court. Just be prepared for a potentially lengthy and expensive process.

Steps to Selling a Co-Owned Property

Ready to take the plunge and sell your co-owned property? Here’s a step-by-step guide to help you navigate the process.

Assessing Ownership Type and Rights

The first step is to determine the type of ownership and understand your rights. Are you in a joint tenancy, tenants in common, or tenancy by the entirety? Knowing this will dictate your next steps.

Communication and Agreement Among Co-Owners

Open and honest communication is key. Get all the co-owners on board and agree on the terms of the sale, including the price and how the proceeds will be distributed.

Legal Consultation and Documentation

Consult a real estate attorney to ensure all legal requirements are met. You’ll need to gather documentation, including the deed, title, and any other relevant paperwork.

Listing and Selling the Property

Hire a real estate agent who specializes in co-owned properties. They can help you list the property, market it, and navigate the sale process.

Closing the Sale and Distributing Proceeds

Once you’ve found a buyer, it’s time to close the sale. This involves signing the necessary documents, transferring the title, and distributing the proceeds among the co-owners.

Legal Options If You Want to Sell and Co-Owners Do Not

What if you’re ready to sell, but your co-owners aren’t on board? Here are some legal options to consider.

Partition Action

A partition action can force the sale or division of the property. It’s a court-ordered process that can be time-consuming and expensive, but it might be your only option if negotiations fail.

Mediation and Arbitration

Before heading to court, consider mediation or arbitration. These alternative dispute resolution methods can help you reach an agreement without the need for a lengthy legal battle.

Forced Sale Consequences

Keep in mind that a forced sale can strain relationships and potentially result in a lower sale price. It’s often a last resort, so weigh the pros and cons carefully.

Using the Expertise of a Local New York Cash Home Buyer

Navigating the sale of a co-owned property can be a daunting task, especially if you’re dealing with disagreements or legal complexities. This is where a local cash home buyer can be a lifesaver.

Cash buyers offer a quick and hassle-free sale, allowing you to bypass the traditional real estate process and avoid potential pitfalls. Whether you’re dealing with co-ownership disputes, facing foreclosure, or just need to sell quickly, a cash buyer can provide a fast, fair offer and help you move forward.
negotiating the sale of a property

Deed and Title Questions Long Island Owners Ask

What does "et al" mean on a deed?

It is Latin for “and others.” The record you are looking at names one owner and is telling you there are more who are not printed on that line. Pull the full deed from the Nassau County Clerk or Suffolk County Clerk to see every name, because every owner named on the deed has to sign for a sale to close.

What are my rights if my name is on the deed but not the mortgage?

You own the house, or your share of it. The loan is not your personal debt, but the mortgage lien sits on the property itself, so if the borrower stops paying, the lender can still foreclose on the house you co-own. The protection you do have: nobody can sell or refinance without your signature.

Can one person sell a house with two names on the title?

No. In New York, every owner on the deed signs the contract and the closing documents, or the sale does not happen. One owner acting alone can sell only their own share, which almost no buyer wants, or ask a court to order a sale of the whole property through a partition action.

Can you sell a house if someone else is on the deed?

Yes, with their signature. Without it, the closing cannot happen. If a co-owner refuses, the realistic paths are a buyout, mediation, or a partition action in court. We have bought Long Island houses in the middle of co-owner disputes, and we will tell you honestly: an agreement between owners is faster and cheaper than litigating one.

Conclusion

Navigating the sale of a co-owned property can often feel like walking a tightrope—balancing legal intricacies, personal dynamics, and the practicalities of real estate transactions. But fear not! With a clear understanding of your ownership rights and a well-thought-out strategy, you can successfully sell a co-owned property without losing your cool or your connections.

  • Clarify Your Ownership: Start by understanding the type of co-ownership you’re involved in—whether it’s joint tenancy, tenants in common, or tenancy by the entirety. Each comes with its own set of rules and implications for selling the property.
  • Communicate Effectively: Open, honest communication with your co-owners is crucial. Whether you’re in agreement or facing disagreements, maintaining a dialogue can help pave the way for a smoother process.
  • Seek Legal Guidance: Don’t go it alone. Engaging a real estate attorney ensures that you’re on solid legal ground, whether you’re negotiating a sale or facing a dispute. Legal expertise can help you avoid pitfalls and navigate complex scenarios.
  • Consider a Cash Buyer: When time is of the essence or co-ownership disputes make traditional sales tricky, a cash home buyer can provide a fast, straightforward solution. This route can help you bypass many of the common hurdles associated with selling a co-owned property.
  • Be Prepared for Challenges: From differing opinions among co-owners to legal obstacles, be prepared for the challenges that might arise. Approach each with patience, a willingness to compromise, and a clear focus on your ultimate goal.

Selling a co-owned property doesn’t have to be a stressful ordeal. By understanding your rights, keeping the lines of communication open, and seeking professional advice, you can navigate the process with confidence. So next time the topic comes up at a family gathering or a casual chat with friends, you’ll be well-equipped to handle it like a pro. After all, knowledge is your best ally in the complex world of real estate.

Remember, each co-owned property situation is unique, and taking the time to understand your specific circumstances can make all the difference. Whether you’re selling Grandma’s cherished home or parting ways with a jointly owned investment, informed decisions will help you achieve a smooth and successful sale.  
Are “We Buy Houses” Companies a Ripoff? Avoiding Scams in NY

If you’ve seen those “we buy houses for cash” signs stapled to telephone poles or received an unsolicited postcard offering to buy your home, your first thought was probably: is this a scam?

It’s a fair question. The “we buy houses” industry includes thousands of legitimate local investors alongside a smaller but vocal group of bad actors who prey on homeowners in vulnerable situations. In New York alone, the Attorney General’s office has pursued cases against fraudulent real estate investors who used deceptive practices to acquire properties below fair value.

This guide breaks down exactly how “we buy houses” companies work, the most common scams and ripoffs to watch for, and a step-by-step process for verifying whether a cash buyer is legitimate before you sign anything.

house sold for cash to a local investor

In this article:

  • How “We Buy Houses” Companies Actually Work
  • Are “We Buy Houses” Offers a Ripoff?
  • 12 Red Flags That Signal a “We Buy Houses” Scam
  • How to Verify a Legitimate Cash Home Buyer
  • Questions to Ask Before Accepting Any Cash Offer
  • What a Fair Cash Offer Actually Looks Like
  • When Selling to a Cash Buyer Makes Sense (and When It Doesn’t)
  • How to Report a Real Estate Scam in New York
  • FAQ: Common Questions About Cash Home Buyers

How “We Buy Houses” Companies Actually Work

“We buy houses” companies are real estate investors who purchase properties directly from homeowners, typically for cash, without requiring the seller to make repairs, stage the home, or pay agent commissions.

The business model is straightforward. These companies buy homes at a discount, renovate them (or hold them as rentals), and then sell or lease the property for a profit. The seller’s benefit is speed and convenience: most legitimate cash buyers can close in 14 to 28 days, compared to the 60 to 90 days it typically takes to sell through a traditional real estate agent on Long Island.

There are several types of cash home buyers operating in New York:

Local real estate investors are individuals or small companies who buy properties in their area, renovate them, and resell them. These buyers tend to have the most flexibility and local market knowledge. We Buy Long Island Homes Fast is an example of a local Long Island investor — founded by Mike Plactere, a licensed New York real estate professional and Certified Public Accountant (CPA) who brings financial transparency to every transaction.

National franchises like HomeVestors (“We Buy Ugly Houses”) and We Buy Houses operate through local franchise owners. Quality varies significantly between individual franchise operators.

iBuyers such as Opendoor and Offerpad use algorithms to make instant offers online. Their offers tend to be closer to market value, but they charge service fees of 5% to 6% and are selective about which properties they’ll buy.

Cash buyer marketplaces aggregate offers from multiple investors, letting sellers compare. Examples include Houzeo and HomeLight’s cash offer platform.

Understanding which type of buyer you’re dealing with is the first step in protecting yourself from potential scams.

Are “We Buy Houses” Offers a Ripoff?

Here’s the honest answer: “we buy houses” companies are not inherently a ripoff, but their offers will be lower than what you’d get selling through a real estate agent on the open market. On average, cash home buyers offer 70% to 85% of a home’s fair market value. That discount reflects the risk the investor takes on (unseen repairs, market changes, holding costs), the cost of renovations, and the convenience they provide to the seller. Here’s a realistic breakdown of how the math works on a $400,000 Long Island home:
Traditional Sale Cash Buyer Sale
Sale Price $400,000 $320,000 (80% of value)
Agent Commissions (5-6%) -$22,000 $0
Repairs & Staging -$15,000 $0
Closing Costs -$8,000 -$2,000 (buyer often pays)
Holding Costs (3-4 months) -$8,000 $0
Net Proceeds $347,000 $318,000
Time to Close 90-120 days 14-28 days
The gap between options is often smaller than people expect once you account for commissions, repairs, and carrying costs. For sellers who need speed, are facing foreclosure, dealing with a tenant-occupied property, or have a home that needs significant work, the math frequently favors a cash sale.

Are “We Buy Houses” Companies Legitimate and Ethical?

Most “we buy houses” companies are legitimate, real businesses that buy homes for cash and close on them. A smaller number are wholesalers or bad actors who use the same signs and the same language, which is why sellers ask this question so often. The difference is not the marketing. It is whether the company is the actual buyer, and whether it behaves honestly once the money is on the table.

A legitimate, ethical cash buyer:

  • Is the buyer, not a middleman. It uses its own funds and closes itself. It does not lock up your house and shop the contract to someone else.
  • Can show proof of funds on request.
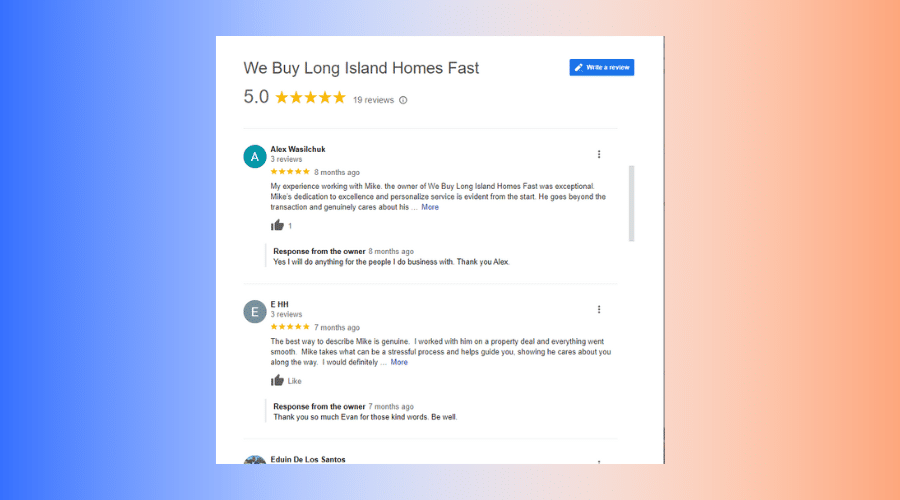
  • Has a verifiable track record: real reviews with specific detail, a real local office, and public records of past purchases.
  • Puts the real number in writing and closes on that number, instead of quoting a high number and renegotiating later.
  • Tells you the truth, including when listing with an agent would net you more.

For a step-by-step way to check any buyer, see how to verify a legitimate cash home buyer further down this page.

As a worked example: We Buy Long Island Homes Fast is a direct buyer, not a wholesaler. Mike Plactere is a licensed New York real estate agent and a licensed CPA, so he answers to professional standards most investors do not. Since 2019 we have bought more than 300 homes on Long Island, over $130 million in property. We hold a Better Business Bureau A+ rating and 42 five-star Google reviews, we pay all closing costs, and proof of funds is available on request. That is what “legitimate” looks like in practice.

What's Your Home Really Worth to a Cash Buyer?

Use our free calculator to see how a cash offer compares to a traditional sale.

$
$25,000
$0$150,000
VS

Traditional Sale

Sale Price
Agent Commissions (5.5%)
Repairs & Stagingincl. typical 25% homeowner overage
Closing Costs (2%)
Holding Costs (3 mo)

Net Proceeds
Timeline 90–120 days

Cash Offer

Offer Range
Agent Commissions $0
Repair Costs $0
Closing Costs ~$0
Holding Costs $0

Net Proceeds
Timeline 7–21 days

Professional cash buyers get better pricing on repairs through established contractor relationships and volume purchasing — typically 20–30% less than retail. The traditional sale column includes a 25% overage buffer because homeowner-managed renovations almost always exceed the original estimate.

Offer = (After Repair Value × 73–88%) – Pro Repair Costs

These real-world cost differences are why cash offers are closer to traditional sale proceeds than most people expect. The multiplier varies based on property condition and local market factors.

Want to see your actual offer? Mike Plactere, licensed CPA and real estate professional, will walk you through the numbers personally.

This calculator provides estimates for educational purposes. Actual cash offers depend on property inspection, local market conditions, and title status. Contact us for a personalized offer.

Why Do Cash for Houses Companies Offer Less Than Market Value?

You might wonder why cash-for-houses companies tend to present offers noticeably lower than what you’d expect on the open market. The answer comes down to their business model and the risks they assume.

These companies specialize in buying properties quickly—often stepping in when a homeowner needs a fast sale due to foreclosure, inheritance, divorce, or extensive repairs. To make the process hassle-free for sellers, they purchase homes “as-is,” absorbing the costs and headaches of upgrades, repairs, and sometimes even legal title issues.

But these perks come with tradeoffs:

  • Lower Offers: To account for repairs, potential holding costs, and their own margin, cash buyers typically make offers below current market value. Their goal is to renovate and resell (or rent) the house at a profit.
  • Risk Factor: Since they’re taking on the responsibility of unseen damage or problems, their offers reflect these unknowns. Essentially, they’re building in a financial cushion just in case the home needs major work.
  • Convenience Premium: Sellers get the benefit of a speedy closing and zero repair obligations, but the price offered reflects the value of convenience.

It’s not a scam if you understand the tradeoff—time and simplicity versus top dollar. For some homeowners, the reduced price is worth bypassing months of showings, negotiations, and open houses. For others, the best value is found on the open market, even if it takes longer.

12 Red Flags That Signal a “We Buy Houses” Scam

Not every “we buy houses” company is operating in good faith. Here are the most common warning signs, based on complaints filed with the Better Business Bureau, the Federal Trade Commission, and the New York Attorney General’s office:

1. They pressure you to sign immediately

Legitimate cash buyers give you time to think, consult an attorney, and compare offers. If someone is pushing you to “sign today or the offer expires,” walk away. Reputable investors know that rushed decisions lead to regret and bad reviews.

2. They won’t provide proof of funds

Any serious cash buyer should be able to show a recent bank statement or a letter from their financial institution confirming they have the funds to close. If they dodge this request, they either don’t have the money or are planning to wholesale your contract to another buyer (often at your expense).

3. The offer seems too good to be true

If a cash buyer offers you more than market value, something is wrong. They may plan to renegotiate after you’ve taken the house off the market, or the contract may contain hidden contingencies that let them back out.

4. They ask for upfront fees

You should never pay a cash buyer to buy your house. No application fees, no “processing fees,” no deposits from the seller. In a legitimate transaction, the buyer puts down earnest money, not the seller.

5. They have no online presence

Search for the company name plus “reviews.” A legitimate operation will have a Google Business Profile, reviews on Google and the BBB, a professional website with a physical address, and verifiable contact information. If they’re invisible online, that’s a problem.

6. They won’t provide references

Experienced cash buyers should be able to connect you with past sellers, a title company they work with, and a real estate attorney they use for closings. Refusal to provide references is a major red flag.

7. The contract has vague or unusual clauses

Watch for overly broad cancellation clauses (“buyer may cancel for any reason”), extended closing timelines (legitimate cash buyers close in weeks, not months), or clauses that allow the buyer to “assign” or resell the contract. Have a New York real estate attorney review any contract before you sign.

8. They discourage you from getting legal advice

Any buyer who discourages you from hiring an attorney is not acting in your interest. In New York, attorneys are typically involved in every real estate transaction. A buyer who tries to skip this step is a red flag.

9. They don’t visit your property

Some scam operators make offers based solely on online data without ever seeing the property. While initial offers can be based on comparable sales, a legitimate buyer will always want to inspect the property before making a final offer.

10. They use a generic email address

Serious real estate companies operate from company email domains, not Gmail or Yahoo addresses. While this alone isn’t definitive, combined with other red flags it suggests the “company” may be one person with no real business infrastructure.

11. Their offer price changes dramatically after the initial offer

Some unscrupulous buyers make a high initial offer to get you to commit, then significantly reduce it after inspection or just before closing when you’ve already made plans based on the original number. This “bait and switch” tactic is one of the most common complaints.

12. They try to bypass the title company or closing attorney

The closing should always go through a licensed title company or real estate attorney. Funds should be wired to an escrow account, not directly to the buyer. Anyone trying to handle the closing informally or outside normal channels is a serious scam risk.

How to Verify a Legitimate Cash Home Buyer

Before accepting any cash offer, run through this verification checklist:

Check the Better Business Bureau

The BBB maintains ratings and complaint histories for businesses. Look for an A or A+ rating and read through any complaints to understand the nature of past issues. An accredited business with a strong rating has met the BBB’s standards for trust.

Read Google Reviews (Carefully)

Google Reviews on a company’s Google Business Profile are one of the most reliable indicators of a company’s reputation. Look for:

  • Volume: A company with 20+ reviews is more trustworthy than one with 2-3.
  • Recency: Reviews from the past 6-12 months indicate the business is active.
  • Specificity: Real reviews mention specific details (the person they worked with, the timeline, the location). Generic five-star reviews with no detail may be fabricated.
  • Responses: Companies that respond to reviews, including negative ones, demonstrate accountability.

Verify Their Real Estate License

In New York, you can verify a real estate license through the New York Department of State’s license search. While not all cash buyers are required to hold a real estate license (investors buying for their own portfolio typically are not), many reputable companies employ licensed agents as part of their team. For example, Mike Plactere of We Buy Long Island Homes Fast holds an active New York real estate license and is also a licensed CPA — credentials you can verify independently through the state’s public databases.

Confirm a Physical Business Address

Search the company’s address on Google Maps. Is it a real office, a residential address, or a virtual office? While some legitimate investors work from home offices, a verifiable business location adds credibility.

Ask for Proof of Past Closings

A legitimate cash buyer should be able to provide:

  • References from past sellers
  • The name and contact information of a title company they regularly work with
  • Examples of past transactions (you can verify these through public records)

Check for Lawsuits and Complaints

Search the company name on the New York State Unified Court System to check for any pending or past lawsuits. Also check the NY Attorney General’s complaint database for any filed complaints.

Questions to Ask Before Accepting Any Cash Offer

Before you commit to any cash buyer, ask these questions and pay close attention to how they respond:

“How did you arrive at your offer price?” A reputable buyer will walk you through their analysis: comparable sales in your area, estimated repair costs, their target profit margin, and how those factors combine to produce their offer. Transparency here is a strong trust signal. You can learn more about how fair cash offers are calculated.

“What happens between now and closing?” Understand the full timeline: when do they inspect the property, when do they finalize the offer, when does the title search happen, and when do you get your money? A legitimate process has clear milestones.

“Are there any fees, commissions, or costs I’ll be responsible for?” Reputable cash buyers cover all closing costs and charge no commissions. Get this confirmed in writing. Some less scrupulous operators bury fees in the contract that effectively reduce your net proceeds.

“Can you provide proof of funds?” This should be a bank statement or letter from a financial institution, dated within the last 30 days. No exceptions.

“What is your earnest money deposit?” A standard earnest money deposit for a cash transaction is 1% to 3% of the purchase price. This money goes to escrow and demonstrates the buyer’s commitment. If they refuse to put down earnest money, they’re not a serious buyer.

“Who handles the closing?” The answer should be a licensed title company or real estate attorney. Ask for the name and contact information so you can verify independently.

“What if the deal falls through?” Understand what happens to your earnest money and what conditions allow either party to exit the contract. A fair contract protects both sides.

we buy houses scams vs verified we buy houses reviews

What a Fair Cash Offer Actually Looks Like

Understanding how cash buyers calculate their offers helps you recognize when an offer is fair versus when you’re being lowballed.

Most legitimate investors use a formula based on the After Repair Value (ARV) of the home:

Offer = (ARV x 70-80%) – Estimated Repair Costs

For example, if your Long Island home would sell for $500,000 after renovations and needs $50,000 in repairs:

  • Conservative offer (70% ARV): ($500,000 x 0.70) – $50,000 = $300,000
  • Competitive offer (80% ARV): ($500,000 x 0.80) – $50,000 = $350,000

If you receive an offer significantly below the 70% threshold without clear justification (major structural issues, environmental problems, extreme market conditions), it may not be a fair deal.

To determine your home’s approximate value, you can check Zillow’s Zestimate, Realtor.com’s home value estimator, or request a professional appraisal.

For Long Island homeowners, our team at We Buy Long Island Homes Fast provides transparent offer breakdowns showing exactly how we arrive at our numbers, so you can see the math for yourself. As a licensed CPA, our founder Mike Plactere walks every seller through the financials line by line — no hidden fees, no surprises at closing.

When Selling to a Cash Buyer Makes Sense (and When It Doesn’t)

A cash sale is often the right choice when:

  • Your home needs significant repairs and you don’t have the resources to make them. Selling as-is to a cash buyer eliminates repair costs entirely.
  • You’re facing foreclosure and need to close before the bank takes action. A cash sale can often stop foreclosure proceedings within weeks.
  • You’ve inherited a property you don’t want to manage, especially if it’s out of state or needs work. Selling an inherited house for cash avoids months of probate delays.
  • You’re going through a divorce and need to liquidate shared property quickly.
  • The property has tenants and selling through traditional channels would require navigating tenant-occupied sale complications.
  • You need to relocate quickly for a job, medical reasons, or a move to assisted living.

A traditional sale is usually better when:

  • Your home is in good condition and move-in ready
  • You’re in a strong seller’s market with high demand
  • You have 3-6 months and no urgency to close
  • Maximizing your sale price is the top priority
  • You have the financial flexibility to cover repairs, staging, and carrying costs while the home is listed

Neither option is universally better. The right choice depends entirely on your specific situation, timeline, and financial needs.

How to Report a Real Estate Scam in New York

If you believe you’ve been targeted by a fraudulent “we buy houses” company in New York, take these steps:

  1. File a complaint with the New York Attorney General at ag.ny.gov/consumer-frauds/filing-consumer-complaint
  2. Report to the FTC at reportfraud.ftc.gov
  3. File with the Better Business Bureau at bbb.org/file-a-complaint
  4. Contact your local District Attorney’s office (for Nassau or Suffolk County)
  5. Report to the New York Department of State if the company claims to hold a real estate license: dos.ny.gov

Document everything: save all communications (texts, emails, voicemails), keep copies of any contracts or agreements, and note dates, times, and names of people you spoke with.

FAQ: Common Questions About Cash Home Buyers

Are “we buy houses” companies legitimate?

Many “we buy houses” companies are legitimate businesses run by real estate investors who provide a valuable service to homeowners who need to sell quickly. However, like any industry, there are bad actors. The key is verifying the company through reviews, licensing checks, proof of funds, and references before committing to a sale. Look for companies with established Google Reviews, a BBB profile, and a physical business address.

How much do “we buy houses” companies pay?

Most cash home buyers offer between 70% and 85% of a home’s fair market value, depending on the property’s condition, location, and needed repairs. The tradeoff is speed and convenience: no commissions (saving 5-6%), no repair costs, and a closing timeline of 1-3 weeks instead of 3-4 months.

Is “We Buy Ugly Houses” (HomeVestors) a scam?

HomeVestors is a legitimate national franchise, not a scam. However, because they operate through independent franchise owners, the experience can vary significantly depending on the individual operator in your area. Always research the specific local franchise you’re dealing with, not just the national brand.

What is the #1 red flag of a “we buy houses” scam?

The single biggest red flag is being asked to pay money upfront. In a legitimate cash home sale, the seller never pays the buyer. If anyone asks you for a fee, deposit, or payment before closing, it’s almost certainly a scam.

Should I get multiple cash offers?

Absolutely. Getting 2-3 cash offers gives you leverage and a clear picture of what your home is actually worth to investors. It also helps you identify outlier offers, both suspiciously high (potential bait-and-switch) and unreasonably low (lowball tactics). For Long Island homeowners, you can request a no-obligation cash offer to use as a comparison point.

Do I need a lawyer to sell my house for cash in New York?

Yes, and this is non-negotiable. New York requires an attorney to be involved in real estate transactions. Any cash buyer who tries to close without legal representation is either uninformed or acting against your interests. Your attorney will review the contract, ensure clear title, and protect your interests at closing.

How fast can a cash buyer close on my house?

Most legitimate cash buyers can close in 14 to 28 days once a purchase agreement is signed. Some can close even faster if there are no title issues. Traditional sales through a real estate agent typically take 60 to 120 days on Long Island.

Can I sell my house for cash if I still have a mortgage?

Yes. The mortgage balance is paid off from the sale proceeds at closing, just like in a traditional sale. The title company handles the payoff directly with your lender. You receive the difference between the sale price and your remaining mortgage balance.

happy homeowners after selling their house for cash

This guide was written by Mike Plactere, founder of We Buy Long Island Homes Fast, a locally owned cash home buying company serving Nassau County, Suffolk County, and the rest of Long Island. Mike is a licensed New York real estate agent and a licensed CPA, a level of financial and regulatory accountability that is rare in this business.

We are a direct buyer, not a wholesaler. We buy your house with our own cash, we close it ourselves, and we renovate and resell it. We do not tie your house up and shop the contract to someone else. Proof of funds is available on request.

Since 2019 we have bought more than 300 homes on Long Island, over $130 million in property. We hold an A+ rating with the Better Business Bureau and 42 five-star Google reviews from Long Island sellers. We pay all closing costs, charge no commissions, and give you a cash offer within 24 hours.

We will also tell you the truth about timing. Some companies advertise a 7-day close. In New York, with attorney review and title work, that is rarely realistic. We give you a cash offer within 24 hours and close on your timeline, honestly.

If you have questions about selling your home for cash, or you want a no-obligation cash offer to see where you stand, get your free cash offer here or call us at (631) 825-8747.

Understanding Home Sale Leaseback Options in New York

Understanding Home Sale Leaseback Options in New York

Owning a home can be a major positive milestone in your life, yet sometimes life’s circumstances can make that dream something of a financial burden. Perhaps you’re facing unexpected bills, looking to downsize in retirement, your children have flown the nest, or simply need access to cash for other investments or debt repayments.

 In such scenarios, a home sale-leaseback arrangement could be the perfect solution for you..

While these arrangements can seem simple on the surface, there’s a fair amount of hidden complexity and depth to how each is structured. That being said, these agreements can offer a unique opportunity to unlock the equity in your home while still maintaining the comfort and familiarity of your current household. 

As such, they serve as a fantastic middle ground for those who want to unlock the value of their home without necessarily altering where they live or how their lifestyle is set up.

In this post, we aim to provide a thorough overview of home sale-leasebacks and will highlight their benefits, potential risks, and practical considerations worth knowing. Without further ado, let’s begin:

accessing home equity before you move out after a home sale

What is a Home Sale Leaseback?

In its simplest definition, a home sale-leaseback is an arrangement where you, the homeowner, sell your property to a buyer while at the same time signing a lease agreement to remain in the home as a tenant. 

As such, you’re trading ownership for tenancy, allowing you to access the equity you’ve built up in your home while avoiding the frustration and unending hidden costs associated with moving. It’s a nice middle ground between a full-house relocation and sale, and not moving at all.

This type of arrangement is often appealing to homeowners facing financial difficulties or wanting to unlock the value of their house, be that when looking to downsize, to free up value for further purchasing power, or to limit some of the extra costs of home ownership. In other words, it helps you unlock the value of the home you’re sitting in, without having to immediately vacate it. For some, that’s a win-win.

How Does a Home Sale Leaseback Work?

The process of a home sale leaseback usually involves the following steps:

  • You, the homeowner, will sell your property to a buyer. This could be an individual investor or a company specializing in these types of transactions. Note that the exact sale structure or terms may alter slightly depending on the country or state you live in, the provider you choose, and the value of the house itself. Compared to conventional selling to other private buyers, this process can be much easier and your home is likely to be approved for sale.
  • Upon that sale, you sign a lease agreement with the new owner, effectively becoming a tenant in your former home. You don’t have to move or relinquish your ability to peaceful enjoyment of the property.
  • You’ll set up a rental arrangement which will be paid to the agreed-upon lease terms, and adhere to the responsibilities outlined in the lease agreement. This tenancy agreement will be separate but bound to the sale. You can negotiate on rent before the full sale is agreed.

This means that the key players that are involved in a home sale-leaseback are you (the seller/upcoming tenant), the buyer (the new landlord), and potentially a property management company if the new owner chooses to outsource the day-to-day management of the property to them. Often, they will be the individuals you deal with, pay rent to, and process maintenance requests toward.

Benefits of Home Sale Leaseback Options

You may be wondering exactly why someone would sell their home to become a tenant in it. Is this not a lesser position to be in? Well, not always. It’s important to remember that not everyone is financially capable of retaining a home, but moving out is not always conducive to their preferred lifestyle or other obligations.

In fact, the benefits can be numerous. Here’s why:

Financial Benefits:

  • You gain immediate access to cash from the sale of your home, which can be used to pay off debts, cover other expenses, prevent the foreclosure of your property, or simply help you unlock the value of your home you’ve worked for.
  • Potential tax benefits, as the sale of your home may be subject to favorable capital gains tax treatment.
  • Avoiding the costs and frustration associated with moving, such as hiring movers, paying for temporary storage, or purchasing a new home – imagine if you could sell your home without any extra fees at all. This is enough for some people.

Flexibility & Stability:

  • You’ll stay in a familiar home and neighborhood, limiting the need to change your entire lifestyle or living area to match your daily routine and community ties.
  • You can negotiate your rental agreement and overall tenancy structure before you make the sale. If you’re not happy, you don’t have to proceed. However, remember that it’s fair for the buyer to offer the general market rate to make the investment worth it.

Investor Benefits:

  • If you’re looking to enter the property market but not live in a home outright, or wish to extend your portfolio, then this can be a good investment while also improving your rental income stream dependably. You may also help someone retain living in their home despite financial hardship.
Getting Money from a home sale before you move out

Are There Many Risks Or Drawbacks To Home Sale Leaseback Arrangements?

Like any investment, there can certainly be risks involved with home sale leaseback arrangements, on both sides of the deal. Let’s go over those a little:

Financial Risks:

  • Leases are arranged on time-limited contracts. This means that if the buyer wishes to raise rent at the end of your fixed term, they are within their rights to do so.
  • Loss of ownership and the ability to build equity in the property is, of course, what you give up in order to unlock the value of your household. This isn’t taken from you but passed to you. However, the asset does become another’s property for future gains.

Legal Risks:

  • While very much legal, shifting lease agreements after the fixed term may change the nature of the current agreement.
  • As a tenant, if you fail to meet the contract terms of the rental, you could be evicted.

Types of Home Sale Leaseback Agreements

There are a number of different leaseback agreements you could opt for. Let’s discuss a few, below:

Short-Term Leasebacks:

These are ideal for homeowners that require temporary financial relief or a transitional living arrangement. In these cases, the lease terms typically range from six months up to two years depending on the investment and value of the household itself.

Long-Term Leasebacks:

If you’re happy to remain a tenant in the property for some time, or the value is extensive, long-term leasebacks have been known to stretch from multiple years to decades.

Fixed-Term Vs. Month-to-Month:

Much like standard private renting agreements, fixed-term leases offer stability, but may not be flexible. In some cases that’s a good thing – it means your rental prices are likely to remain the same for that period.

However, month-to-month leases provide more worthwhile flexibility but can still be subject to rent increases or contract termination should a tenant break it, with shorter notice periods.

Who Should Consider A Home Sale Leaseback?

While home sale leasebacks can benefit a wide range of homeowners and not only during financial hardship, they are particularly well-suited for certain groups:

Ideal Leaseback Candidates

  • Homeowners who might need immediate liquidity to address financial difficulties or simply feel free from the cost of home ownership. It’s a popular option for those living in older homes with high value but extensive maintenance costs.
  • Retirees looking to access their home equity while maintaining their current living situation – can then pass this value down to their families.
  • Individuals looking to invest in other options while still living in their household.

The truth is that almost anyone can benefit from unlocking the value of assets they own, while still using that asset. We rarely see this in other loan or selling agreements, and so such outcomes can provide a fantastic alternative for those who would otherwise have to move.

Questions To Ask:

It’s wise to ask a few questions and make sure you’re completely sure of the terms before you enter into this agreement and sign over your home. Here are some suggestions:

  • What are the specific lease terms, including the duration, rent amount, and any renewal options once it lapses?
  • Who will be responsible for maintenance, repairs, and property taxes (this can differ depending on where you live and the provider itself)?
  • Are there any buyback options or opportunities to purchase the property back in the future, should my financial situation change at all?

How Do I Negotiate A Home Sale Leaseback?

Ultimately, if you have an asset to sell, then you’re in a good position to get favorable terms. 

First,  thoroughly research market rates for similar rental properties in your area to ensure you’re securing a fair deal and aren’t being short-sold. You can consider negotiating for favorable terms from there, such as a longer lease duration, rent control provisions where appropriate, or the inclusion of maintenance responsibilities for the landlord. 

Remember not to give away your rights or opt for a quick sale – investors tend to accept conditions if the long-term benefit is favorable.

From there, consult with a real estate lawyer or financial advisor to ensure you fully understand the legal and financial consequences of the agreement, and that all documents are approved before signing.

To conclude, a home sale-leaseback can be an effective solution for homeowners seeking financial flexibility, access to freed-up equity, or more favorable living costs without necessarily giving up their home.

However, it’s essential to carefully evaluate your personal circumstances where appropriate and to understand the potential risks and drawbacks as part of this, and negotiate suitable terms. Don’t just jump into any deal.

getting money from a home sale up front to pay for moving expenses

Contact We Buy Long Island Homes Fast Today!

At We Buy Long Island Homes Fast, we are proud to offer competitive home sale-leaseback arrangements and have curated many happy clients over our years of servicing the Long Island market. Our fair offers allow you to sell as-is without making repairs, and our cash offers are entirely without obligations, freeing you of those hidden realtor fees no one wants.

Why not contact us today? We’d be delighted to take your call and help you understand your options.

Inheriting a House that is Paid Off

Inheriting a House that is Paid Off in New York

Inheriting a house that has been paid off can be a significant event in a person’s life. Not only is it an emotional connection to the past so soon after the passing of someone you recently lost, but it represents a solid financial asset too. For residents in the state of New York, understanding how to deal with an inherited property is essential. There are various factors to consider, so let’s show you how to handle an inherited house that has been paid off, including the following:

  • Legal obligations.
  • Tax implications.
  • Options for selling the property.
inheriting a paid off house in new york

Understanding Your Inheritance

When you are inheriting a house that has been fully paid off, there are a number of key factors that come into play, including assessing the property’s condition. One of the key steps is to conduct a thorough inspection of the property and identify the following:

  • Structural issues.
  • Maintenance needs.
  • Necessary repairs.
  • Determining the fair market value of the property based on all the repairs and all the utilities.

Hiring a professional inspector can offer you insights into the condition, and obtaining an appraisal will help you to determine the accurate market value, which is essential for the tax assessment and potential sale of the property.

Legal Transfer of Ownership

Transferring the ownership of an inherited property typically requires going through the probate process, especially if the deceased did not leave behind an estate plan or a will. Probate is the legal process where a recently deceased person’s assets are distributed to other heirs and beneficiaries, and any remaining debts are settled. When inheriting a house that’s fully paid off with no outstanding mortgage, the probate administration process involves several key steps:

Initiating Probate

If the deceased had a valid will, the executor named in the will must file the original will and a certified copy of the death certificate with the Surrogate’s Court in the county where the deceased resided. The filing needs to include a probate petition listing all of the beneficiaries or other family members or heirs (distributees) who are entitled to inherit the estate. Before the court approves this, it is essential for all distributees to be officially notified of the probate proceeding.

The Home’s Appraised Value

During probate, the value of the debt-free home will be appraised to determine if any New York state estate tax is owed and applies to estates valued over $6.94 million gross as of 2024.

Transferring Ownership

Once probate is completed and any tax is paid, the court will issue an order to officially transfer ownership of the mortgage-free home to the beneficiary/beneficiaries named in the will. The new owner/owners must record the deed transfer at the County Clerk’s office to establish their ownership.

If there are multiple heirs named in the will, they will need to agree on what to do with the inherited house, which typically involves:

  • Keeping it.
  • Selling it.
  • Having one heir buy out the other’s shares.

Disagreements among heirs can complicate the probate process and delay the distribution of these assets, but a probate attorney can help with mediation and facilitate smoother communication.

tax implications of inheriting a paid off house

Understanding the Tax Implications

Inheriting property can have significant tax implications both at the state and the federal levels. In New York, there is no inheritance tax, so the heir does not need to pay taxes on the value of the inherited house itself. But other taxes like federal estate taxes may apply depending on the circumstances of the inheritance.

Estate Tax

If the total value of the deceased’s estate exceeds the estate may be subject to New York’s estate tax before assets like the house are distributed to heirs. Estate tax rates and exemptions can change over time. For dates of death on or after January 1, 2024, the basic exclusion amount is $6.94 million, meaning that the first $6.94 million of an estate is exempt from New York estate tax. 

To minimize this, the decedent could gift portions of the property to beneficiaries annually during their lifetime up to the annual gift tax exclusion amount, which as of 2024 is $18,000 per person. It’s important to note that while New York does not have a gift tax, gifts made within three years of the death are included in the decedent’s estate for New York estate tax purposes, known as the clawback rule. 

While it’s possible to give up to $18,000 per person per year without any gift tax consequences, those gifts may still be subject to New York tax if the donor passes away within three years of making the gifts.

Capital Gains Tax

If the heir/heirs decide to sell the inherited house, they may need to pay capital gains taxes on any increasing value from the stepped-up basis to the estate sale price. A stepped-up or step-up basis means the home’s value for tax purposes is reset to the fair market value at the time of the decedent’s death rather than the original purchase price, which minimizes the capital gains if the house is sold soon after the inheritance. 

Understanding this stepped-up basis is crucial to accurately calculate the tax liability when selling the property. You do not pay capital gains tax on the inheritance itself, and the tax is only levied when you sell the property and is calculated on the gain made since you inherited it. In New York State, capital gains taxes rates range from 22% to 30% depending on the type of property and the length of time it was owned. For example, for someone who inherited a property and sold it after owning it for more than one year, the capital gains tax rate would be 22% if the property was held individually. 

If you sell the property you have inherited, you will need to pay capital gains tax on the gain made since you inherited it, and this gain is calculated by subtracting the stepped-up basis from the sale price. For example, if you inherited house dwellings for $500,000 and sold it for $600,000, the taxable gain would be the difference between the two: $100,000, and you would owe capital gains tax on this $100,000 gain. Proper tax planning and consultation with a tax advisor are essential to minimize capital gains tax liability.

inherited property options in new york

Exploring Your Options With Your Inherited Property

You have a few options available to you when you are inheriting a house that is paid off:

Keep the Property

Keeping the property may be a desirable option if it holds sentimental value or if you intend to use it as your primary residence or a holiday house. However, it’s essential to consider the ongoing expenses associated with this type of homeownership, including:

Paying property taxes in New York can vary widely depending on a variety of factors:

  • Property location.
  • Size.
  • Assessed value.

It’s essential to budget for these expenses to ensure you can afford to keep the property in the long term.

Sell the Property

Selling the inherited property might be the best option if you are not interested in keeping it or if you need to liquidate the assets to cover other expenses or debts in your life. When you are selling a property in New York State, you have a number of options available, including:

  • Listing it on the open market with a real estate agent.
  • Selling it at auction.
  • Selling it directly to a real estate investor.

Each option has its pros and cons and can depend on a variety of factors like the market demand, the condition of the property, and your particular timeline for selling. If you choose to sell the property, it’s essential to consider the potential costs such as:

  • Real estate agent commissions.
  • Closing costs.
  • Capital gains tax.

Working with a local and reliable buyer who specializes in buying inherited properties can help streamline the selling process and ensure a fair outcome.

Donate the Property

Donating the inherited property can be a meaningful option, especially if you’re looking to support a charitable cause or mission that you believe in. Donating your real estate can also provide tax benefits:

  • If you donate an appreciated property held for longer than one year, you can eliminate capital gains tax on the property.
  • You can claim a charitable deduction for the full value of the donated property as determined by an independent appraisal, which can significantly reduce your income tax obligations for the year.
  • Once the property is donated, you no longer have to worry about having to pay property taxes, insurance, maintenance, or the costs associated with owning the property.

Before you donate real estate, you also need to consider if the property has any outstanding debts. In this case, the IRS may consider it a “bargain sale,” defined as the sale of property to a charitable organization for less than its market value, which triggers some capital gains tax. If you have a pre-existing sale agreement in place, this could be seen as an “anticipatory assignment of income” (which prevents taxpayers from assigning income to another party before it is earned) by the IRS.

It’s important to consider the practicalities and potential challenges of donating property, for example, finding a qualified charitable organization willing to accept the donation and transferring the ownership legally while navigating any tax implications. This is where a tax advisor or estate planning attorney can help.

challenges with inheriting a paid off house

Understanding the Challenges of Inheriting a House

Inheriting a house that is paid off can, in many ways, be an amazing outcome despite the situation, but it’s also important to note that there can be a number of challenges at play, including the following:

Maintenance and Upkeep

Inheriting a house comes with ongoing maintenance and upkeep responsibilities, from routine maintenance tasks to lawn care landscaping, as well as the more significant repairs like plumbing issues or roof replacement. It is essential to budget for these expenses while also planning for regular maintenance to ensure the property remains in good condition and retains its value over time, especially if you plan on selling it at some point.

Emotional Considerations

Inheriting a house can evoke a wide range of emotions, from nostalgia and sentimentality if it was a house you grew up in, to grief and loss that you may not have had time to process. One of the biggest challenges in inheriting a property is the emotional one. 

If you’ve recently lost a close family member and are navigating family dynamics and relationships at the same time, deciding what to do with the inherited property can be a deeply personal decision that requires weighing up the financial considerations against the emotional attachments. It is essential to give yourself the time and space to process your feelings and seek support if needed.

Financial Considerations

While inheriting a house that is paid off means there is no mortgage attached, this doesn’t necessarily mean the property’s financial obligations stop there. There are ongoing expenses that must be accounted for when inheriting a property, such as:

  • Maintenance costs.
  • Utility bills.
  • Insurance premiums.
  • Property taxes.

Property taxes can be a significant expense, especially in high-value areas like Long Island, and it’s essential to budget for these expenses and factor in any additional homeownership costs like upgrades, renovations, and repairs. Therefore, consulting with a financial advisor or estate planning professional can help you to develop a proper financial plan.

Conclusion

When you are inheriting a house that is paid off, it’s important to understand that there’s a variety of considerations at play. There can be a number of challenges in inheriting a house, but this is where local companies like us can help. 

We purchase inherited houses as is, without you needing to make any changes to the propert,y like repairs, updates, or even cleaning it. We can also help you to work through any of the legal probate processes or tax issues that can occur when you inherit property. 

We understand the unique challenges of dealing with inherited houses, providing certainty and peace of mind, knowing you are working with a reliable real estate company that understands inherited properties. It doesn’t need to be a complex procedure, so contact us, and let’s help you navigate the process of inheriting a house that is paid off without any of the emotional considerations.

How To Find Comps in My Area of New York

How To Find Comps in My Area of New York

If you are considering selling a property in New York State, understanding the market value of the homes in your area is essential for a number of reasons: 

  • It allows you to price your home accurately and competitively. Overpricing can deter buyers while underpricing leaves money on the table. When you analyze recent comparable sales, known as comps, of similar nearby homes, this provides the best gauge of your property’s market value. 
  • Helps you understand if the price is out of line with the market.

    Properly pricing based on comps shows that you understand the local market and are not just guessing.

    • Sets buyer expectations. The listing price that’s accurate based on comps ensures you attract the right buyers from the very outset.
    • Facilitates smoother selling. Lenders can require an appraisal, so if your price is significantly higher than the appraised value based on comps, this can derail or delay the sale entirely. Overpricing leads to a stale listing that will sit on the market, but an informed pricing strategy based on comps will result in a quicker sale.

    It’s important to remember that pricing a home isn’t as simple as doubling the price if your home is twice the size of a comparable one down the street. There are many factors that go into home pricing, and taking shortcuts by using poorly matched comps or making broad assumptions can steer you off course. Comp selection requires careful attention to details like size, age, location, condition, and amenities to ensure your price truly reflects market realities. Taking this step seriously not only protects your interests but also makes the entire selling process more predictable and successful.

finding real estate comps for my house in new york

Factors to Consider

Before diving into the process of finding comps, it’s essential to understand the key factors that can influence property values in your area:

Location

Location is considered the most critical factor in real estate. In New York State, factors like school district, neighborhood, proximity to amenities, public transportation, and so much more can significantly impact the value of a property. 

Properties in desirable neighborhoods with good schools and easy access to transportation tend to command higher prices, and properties located in areas experiencing gentrification or revitalization may also see an increased demand, which transforms into higher prices.

Property Characteristics

The characteristics of a property play a significant role in determining its value, with a number of key factors that contribute to a property’s appeal and marketability such as:

  • Size
  • Layout
  • Age
  • Condition
  • Architectural style

Larger properties with a larger number of bedrooms and bathrooms will typically fetch higher prices, but properties with desirable features like granite countertops, hardwood floors, and updated contemporary appliances may command premium prices.  Features like solar panels when selling a house have mixed reviews and shouldn’t be given any extra value based on market preferences.

Market Trends

Understanding the current trends in the local real estate market is essential to gauge property values. There are a range of influences on real estate market trends including:

  • Demographic trends
  • Interest rates
  • Economic conditions
  • The supply and demand dynamics

There are so many different factors at play. For example, if there is a high demand for homes in your area but there’s limited inventory, prices may increase because of competition among buyers, and conversely, if there’s an oversupply of homes on the market, this can result in a decrease in price as sellers compete for buyers’ attention.

Seasonality and Its Impact on Comparable Sales

When examining comps to determine your property’s market value, it’s important not to overlook the effects of seasonality. The real estate market in New York State, much like many regions, experiences shifts throughout the year that can influence both how long homes remain on the market and the final sale prices achieved.

Homes tend to attract more buyers and sell at a brisker pace in the spring and early summer months, often resulting in higher sale prices simply due to increased demand. Conversely, winter tends to be a slower season—fewer buyers are actively searching, and homes can linger on the market, sometimes prompting sellers to lower prices to entice cautious purchasers.

Because of these patterns, comps pulled from the height of the spring market may not be accurate benchmarks for pricing your home during a quieter winter month, and vice versa. To ensure the comps you use are truly relevant, always consider what time of year the sales occurred. Prices can fluctuate not just based on property characteristics but also on when a transaction takes place, so prioritizing comps from the same season as your listing can lead to a more realistic and effective pricing strategy.

There are so many different factors at play, for example, if there is a high demand for homes in your area but there’s limited inventory, prices may increase because of competition among buyers, and conversely, if there’s an oversupply of homes on the market, this can result in a decrease in price as sellers compete for buyers’ attention.

Recent Sales

Analyzing recently sold homes in your area can provide valuable insight into determining the market value. Be sure to look for properties similar to yours in terms of condition, location, and size, that have sold within the last few months. 

Factors like price per square foot, recorded sales price, and the number of days on the market can help you get a sense of the current market conditions. It’s important to keep in mind that recent sales data is more reflective of current real estate market trends rather than older sales data, so prioritize analyzing the most up-to-date information you can.

Comparable Properties

Identifying properties similar to yours is essential for accurate comparisons. Looking for comps in the same neighborhood or area, with similar features and amenities, and sold recently can help you to better estimate your property’s market value.

When searching for comparable properties, pay close attention to the type of home. If your property is a single-family home, limit your comparisons to other single-family homes. Likewise, if you’re pricing a condo, focus only on other condos in the area—comparing across different types like condos, townhouses, and single-family homes can lead to misleading conclusions about value.

It’s essential to not just consider the similarities, but also the differences between determining comps because you may have to adjust based on factors like upgrades, condition, and size to ensure accurate comparisons.

By narrowing your comps to properties that truly “match” yours in type, as well as location, features, and sale date, you’ll have a much clearer picture of your home’s likely market value.

How Buyers Leverage Comps When Making an Offer

When buyers are preparing to make an offer on a home, real estate comps become their secret weapon for negotiating confidently. By reviewing recent sales of similar properties in the same neighborhood, buyers can get a clear picture of what comparable homes have actually sold for—not just the listing prices, but the amounts that closed the deal.

Armed with this knowledge, buyers can:

  • Avoid Overpaying: They’ll know if a seller’s asking price is fair or inflated, helping them set a competitive but reasonable offer.
  • Strengthen Negotiations: If needed, buyers can present solid evidence—recently sold properties that match the home’s features and location—to justify their offer.
  • Spot a Good Deal: Sometimes, comps reveal when a home is priced below market value, allowing buyers to act quickly before someone else snaps it up.
  • Understand Market Trends: Tracking comps over time helps buyers sense if values are rising or falling in the neighborhood, so they can strategize accordingly.

In short, buyers turn to comps to make smart, informed decisions—ensuring they pay the right price for their next home.

The Importance of Keeping Detailed Notes

When you’re researching comparable properties, keeping thorough notes is absolutely vital. Over time, much of the rich detail from property listings—like listing photos and descriptive remarks—can disappear from online records, leaving behind only the basics (such as square footage, address, and sale price). That’s not enough data to make meaningful comparisons or defend your conclusions later.

By documenting all the pertinent details the moment you find a strong comp—things like the condition, upgrades, special features, visual appeal, and even quirks noted in the original listing—you’ll have a much more robust and accurate reference point. This careful record-keeping ensures you can revisit and verify your analysis even if original listings are removed or archived. Think of it as building your own personalized database you can trust, even after the original information has faded from view.

What is the Process to Find Comps?

Now we’ve covered the key factors, so let’s show you how to best find real estate comps in New York State: 

finding my home value online in new york

Utilizing Online Resources

There are a number of excellent resources available, including:

Real Estate Websites

Real estate websites provide access to a vast database of property listings and sales data. These sites allow you to search for recently sold homes in your area, and you can filter results based on various criteria such as location, price range, and property type. Real estate websites help you identify comps because you can look at the following:

  • Historical sales data
  • Property details
  • Photos

All this information can add up to ensure that you identify comps in your area.

Look Closely at Listing Photos

When viewing these sites, pay special attention to the listing photos. Carefully scan the pictures for details—does the home have finishes similar to yours? Examine things like appliances, fixtures, and flooring. Even seemingly small differences, such as stainless steel appliances versus older white ones, can influence a property’s value. These details matter when comparing homes and making adjustments for differences between your property and the comps you find.

Bear in mind that while online resources can be a good starting point, they may not always provide the most accurate or indeed up-to-date information. You need to verify the information you find on real estate sites with other sources, for example, public records.

Automated Valuation Models (AVMs)

After gathering comparable sales and narrowing down your estimated price, it’s smart to cross-check your findings using automated valuation models, commonly known as AVMs. These online tools use a blend of public data—such as recent sales, property characteristics, local market trends, and tax records—to calculate an estimated value for your property.

To use an AVM, simply enter your address into well-known real estate platforms that provide this feature. Most platforms will instantly generate an estimated value and may also share recent sales and historical trends in your neighborhood, offering useful context for your pricing decision.

Keep in mind, though, that the accuracy of these estimates will depend on how much up-to-date and comprehensive data is available for your area. Urban locations with detailed property records tend to produce more reliable estimates, while rural or less-documented areas might have larger error margins.  Be careful when comparing different areas to each other.  For example, a house sold in Levittown might be worth more or less than a house in Brentwood purchased by an investor. 

You can further improve the precision of automated valuations by making sure your home’s details—like square footage, the number of bedrooms and bathrooms, and recent renovations—are up to date on these platforms. Providing current and accurate information will help ensure the valuation reflects your property’s true value.

What Factors Affect the Accuracy of Automated Valuation Tools?

Automated valuation models, often found on major real estate websites, use a variety of data points to estimate your home’s value—but their accuracy can vary quite a bit depending on several factors.

These estimates draw from public records, recent sales, tax assessments, and available details like square footage, bedroom and bathroom count, age, and renovations. The more up-to-date and comprehensive the local data, the closer the estimate will be to what your home might actually sell for.

Keep in mind:

  • Areas with robust and frequently updated public records tend to yield more precise estimates.
  • Unique features, recent upgrades, or distinct architectural styles may not always get captured, potentially skewing the numbers.
  • Market conditions and trends—like shifts in demand or fluctuations in local inventory—also have a direct impact.

Ultimately, while these online estimations can offer a quick reference point, they should be considered a starting place, not the final word, and are best supplemented with local data and insights from real estate professionals.

Providing More Detailed Information

Offering comprehensive and up-to-date details about your property can make a significant difference when it comes to automated home valuations. The more accurate and extensive the data—such as recent renovations, unique features, or updates to kitchens and bathrooms—the more precise these estimates can become.

Automated valuation tools pull data from public records and listing services, but those sources may overlook upgrades or changes that set your home apart. By thoroughly documenting improvements, additions, and standout amenities, you help ensure that automated estimates better reflect your property’s true value.

Taking the time to submit this information through online platforms or even directly to real estate agents strengthens the quality of comps used for your property, giving you a more realistic market snapshot.

Multiple Listing Service (MLS)

If you are working with real estate agents, they can pull comps directly from the MLS, which is a comprehensive database used by real estate professionals. The MLS contains detailed information about properties listed for sale and recently sold properties, including:

  • A listing description such as the property’s features, upgrades, condition, lot size, etc.
  • Interior and exterior photos
  • Property details including square footage, bedrooms, bathrooms, etc.
  • List price and listing history
  • Sale terms such as whether the property is being sold as-is or has any contingencies, etc.
  • Private remarks (which are only visible to other agents)

By making the most of an MLS, you can get a more comprehensive understanding of the market so you can find accurate comps.

Don’t Overlook the Listing Description

While it’s easy to focus on the photos and basic property stats, make sure you carefully read the listing description for each comparable property. Not every improvement or upgrade is visible in pictures—details like a new roof, updated plumbing, or energy-efficient systems can significantly affect a home’s value, even if they aren’t obvious at first glance. Reading the full listing description ensures you catch these upgrades, which helps you make better, more accurate adjustments when comparing properties.

Online Sites

There are other online resources that can help you find comps in your area, such as local real estate brokerage websites and other popular resources like Homes.com provides valuable information about recent sales and property values. 

Bear in mind that while online sites can be useful for research, they may not always have the most up-to-date or comprehensive information, and therefore you should consider cross-referencing information from multiple sources to guarantee accuracy. This is especially true if you are looking up mortgage information online.  Data aggregators typically aren’t equipped to correctly report unique mortgage products like reverse mortgages, HELOCs, or ARM loans.  Make sure you are getting accurate data from your online source if you are going to use this information to determine the sales price for  your home.

Considering the "Like New" Condition

It’s essential to note that most comparable sales online are of houses that are in “like new” condition. If your property needs updates or repairs, the comps you find online might not accurately reflect its fair market value. Many online listings feature properties that have been staged or renovated to appeal to buyers, and this can skew perceptions of value. 

If your property is in need of repairs or updates, reaching out to a reputable real estate company that specializes in assessing properties in as-is condition can provide you with more accurate valuations based on your property’s current condition and the potential value after renovations.

Consult with a Real Estate Agent

Hire a Licensed Agent

Real estate agents have a wealth of knowledge, of course, and can provide valuable insights into finding accurate comps. Licensed real estate agents have access to exclusive resources and tools to analyze market trends and property values. 

When choosing a reputable agent, look for someone who has experience in your local area and has a track record of providing successful transactions. A good agent will take the time to understand your needs and provide personalized guidance throughout the process so you can benefit from their expertise and access to MLS data to find comps that reflect your property’s value.

Keep in mind that when a real estate agent is providing you with a value of your home, they are going to likely want to list your home for sale which includes commissions, fees, closing costs, and more.  This can be a valuable service if a house is in pristine condition.  However, if a house has some normal wear and tear or needs a little TLC, a traditional agent can struggle to sell quickly in these circumstances.

A Comparative Market Analysis (CMA)

The agent can conduct a comparative market analysis to assess the value of the property based on recent sales and market conditions, which involves comparing the property to similar homes that have recently sold in your area, taking into account key factors like location, size, and condition. 

By analyzing comps and the market data, a real estate agent can determine a competitive listing price when selling. A CMA is a valuable tool for understanding the current market value of the property and can provide valuable insights for pricing strategies and negotiations.

MLS Comps

As a real estate agent can pull comps directly from the MLS, you can get detailed information about recently sold properties in your area. In addition to the information above as to what an MLS can do for you, an MLS comp is considered more reliable than information obtained from public websites as they can come directly from real estate professionals and are kept updated in real time. 

Analyzing MLS comps can identify trends, assess market conditions, and determine the most appropriate pricing strategy for the property. By leveraging MLS data, you can make more informed decisions and maximize the value of your real estate investment.

using the mls to find comps for my house value

Review Public Property Records

An excellent way to find comps is to find public property records. The county’s public property records contain valuable information about real estate transactions, including sales prices and property details. These records are typically maintained by the County Assessor’s office and are available to the public. 

You can access public property records online through the county’s website or visit the county assessor’s office in person. In New York State, most real property records, including deeds and mortgages, are maintained by the County Clerk’s office. 

For properties located in New York City’s boroughs Queens, Brooklyn, Bronx, and Manhattan, the Automated City Register Information System (ACRIS) provides a wealth of information. Additionally, title companies have access to comprehensive property records databases, and for a fee, you can get a title report containing the full history of ownership as well as any encumbrances on a property.

Attending Open Houses and Real Estate Auctions

Another way to observe features and conditions of comparable properties is through attending open houses and real estate auctions, which ensures that you can observe firsthand comparable properties while also giving you an opportunity to network with others such as real estate professionals, and gather valuable market insights. 

When doing this, it’s essential to take note of asking prices and selling prices as well as any features or amenities that may affect their value.

Off Market Homes

Off-market homes, also known as pocket listings, are properties that are for sale but not actively advertised on real estate websites or the MLS. These properties can be valuable comps for determining market value, and these types of homes often offer unique opportunities that may be priced differently than properties listed on an open market, ensuring that you have a complete picture of the conditions of the market.

Hire a Professional Appraiser

If you require a precise valuation of your property, a professional appraiser can be an invaluable resource. An appraiser considers various factors to determine a fair market price, including:

  • Market trends
  • The property condition
  • Recent sales data

Bear in mind that hiring an appraisal will incur additional costs; however, if you are looking for an accurate valuation, this can be very useful in pricing strategies, negotiations, and decision-making. 

When hiring a professional appraiser, look for someone who is licensed and experienced in your local market as they will have a thorough understanding of local market conditions and factors that influence the property values. 

You will need to provide the appraiser with comprehensive information about your property, such as recent improvements or renovations, as well as any relevant comps you have identified. Professional appraisers use standardized methods and techniques to assess property values objectively so you can obtain a reliable valuation that reflects the true market value of the property.

Conclusion

If you are trying to find real estate comps in New York, it’s vital to make informed decisions. There are a number of key factors you need to consider, such as recent sales data, property characteristics, location, and market trends, to help you gain valuable insights into the local real estate market. 

If you want to understand your home’s value from an as-is perspective, this is where we can help. Reach out to us as we can help you understand your home’s value from an as-is perspective so you can gain an accurate comp to achieve your selling goals.

Who Pays Closing Costs When Selling a House on Long Island?

Who Pays Closing Costs When Selling a House on Long Island?

Real estate transactions aren’t as straightforward as buying something from a store or online. They involve many other costs aside from the purchase price of the property.

Closing costs are the most common fees associated with property transactions. These may differ depending on your location, but you can expect to pay these extra costs when you sell your home on Long Island.

Usually, sellers and buyers share these costs. The split depends on the specific terms of the sale agreement and negotiations between the parties. 

Read on to find out more about closing costs on Long Island before you sell your house.

real estate closing costs in new york

Understanding Closing Costs on Long Island

Closing costs is the broad term for all the additional costs over and above the property’s sale price. These costs are mandatory during traditional real estate sales.

You cannot conclude a real estate sale without paying the closing costs, which are usually split between the buyer and the seller.

There are two types of closing costs, i.e., bank-related costs and title-related costs. The following are examples of closing costs for sellers in Nassau County:

  • Real estate agent commissions
  • Title insurance
  • Title service fees
  • Real estate transfer tax
  • Property taxes prorated up to the closing date
  • Attorney fees
  • Recording fees
  • Prorated HOA fees, if applicable

Some sellers offer a home warranty to entice potential buyers, and this would also form part of the closing costs

In Nassau County, the seller usually pays the larger portion of the closing costs. These taxes and fees can amount to as much as 6% to 10% of the home’s value.

Buyers typically pay for the following:

  • Loan origination fees
  • Mortgage recording tax
  • New York Mansion Tax for property valued at over $1 million
  • Title Insurance
  • Land survey fee
  • Lead-based paint inspection

The above is a general breakdown of how closing costs are split in New York, but they may vary depending on the conditions of the sale and other specifics related to the property. Either party may pay all or some of the closing costs.

In most cases, sellers don’t pay closing costs out-of-pocket at the closing table. These are usually deducted from the money received at the sale, so they impact how much you receive from the sale of your home.

closing costs when selling house for cash on long island

Closing Costs: Cash Buyer vs. Loan Buyer

Cash buyers can avoid many closing costs associated with a home sale as they don’t need to apply for a mortgage. That means they don’t pay the costs associated with home inspections, home appraisals, mortgage tax, and loan origination fees.

Due to these savings, sellers can often negotiate with them to pay some or all of the other closing costs associated with the sale.

Benefits of Selling to a Cash Buyer

Selling your home to a cash buyer is a much faster and often easier process than selling to a mortgage buyer. When you sell your home to a cash buyer, you enjoy the following benefits:

Avoid Contingencies

Cash buyers do not need to apply for a mortgage. That means you won’t lose your sale if the buyer is unable to achieve mortgage approval. 

You can also avoid sale contingencies since you don’t need to wait long for the sale of your home before buying another one.

No Home Appraisals

When you sell to a cash buyer, you avoid the time delays associated with a mortgage-lender-mandated home appraisal. Some cash investors might ask for an appraisal to ensure they’re getting their money’s worth, but that rarely happens. 

Simplified Closing Procedure

When you close on a cash sale, you only need to sign the settlement statement, title, and deed. The buyer pays the purchase price via wire transfer or cashier check, greatly reducing the paperwork involved in the transaction. 

Less Hassle and a Faster Sale

Selling your home for cash means you won’t need to carry out any repairs mandated by the mortgage lender, and you can skip paying a real estate agent’s commission, too.

These fees are currently around 6% of the home’s sale price, but they could change soon depending on an upcoming NAR court case.

Seller Closing Costs for a Cash Sale

There are some unavoidable closing costs associated with every home sale, cash or otherwise. These include:

  • Legal fees
  • A title search
  • Realtor’s commission, if applicable
  • Home warranty
  • Transfer taxes
  • Prorated property taxes

Some national or corporate cash home-buying companies also charge a service fee when they buy your home for cash while other local homebuying companies will take care of these fees to deliver a straigtforward offer.

Negotiating Closing Costs with Cash Buyers

Some buyers, including cash buyers, will ask the seller to pay some or all of the closing costs on their property. If you agree to this, you should make sure you increase your price accordingly.

Getting the buyer to pay closing costs is a little more complicated, but it’s easier if there’s a high demand for your property. In this case, you can include payment of the closing costs as part of the sale conditions.

You can create demand by staging the home, marketing it intensively, or completing desirable upgrades. In many cases, all this time, expense, and effort may outweigh the benefit of avoiding the closing costs. 

If you want to avoid paying seller closing costs out of your pocket, it’s best to find a cash home-buying company that will pay the costs on your behalf and then deduct them from their offer. 

sell a long island home without paying closing costs

Sell Your Long Island Home for Cash

Selling your home for cash is a good way to avoid many of the closing costs associated with real estate sales. A cash sale doesn’t need to include realtor commissions, mortgage origination fees, or home inspection costs.

When you sell to the right buyer, you can reduce your closing costs even more.

When you sell your home to We Buy Long Island Homes Fast, our offer includes all your closing costs, helping you save time and skip the hassles associated with conventional home sales. We can close in just 14 days, and we buy homes as-is, eliminating the need for cleaning, upgrades, and repairs.

Get a fair cash offer for your Long Island home today.

What Makes a House Uninhabitable on Long Island

Homeownership on Long Island embodies the ideals of safety, security, and a personal sanctuary. Yet, the harsh reality of encountering conditions that make a dwelling unsuitable for living can shatter this dream, replacing comfort with concern and stability with stress.

In this article, we aim to shed light on and provide solutions for homeowners wrestling with the critical question: What renders a house uninhabitable on Long Island?  Oftentimes, a home becomes uninhabitable when it has been vacant or abandoned, damaged by tenants, or inherited and proper repairs or updates haven’t been made in a long time. 

Of course, there are other reasons why a home can become uninhabitable such as flooding, serious mold growth, and animal or bug infestation.  Join us as we navigate through these challenging scenarios, offering both clarity and direction.

example of uninhabitable house on long island

Understanding Uninhabitability on Long Island

“Uninhabitable” homes, as defined broadly, are those deemed unsafe or unsuitable for living due to severe deficiencies. In the Long Island context, a property might be considered uninhabitable if it lacks essential utilities like running water, suffers from critical electrical system issues, or has significant structural damage posing risks to occupants. 

Long Island homeowners should be cognizant of specific conditions that might not be immediately obvious, such as hazardous materials like asbestos or lead paint, which can render a house uninhabitable under state laws. Moreover, the absence of basic amenities like hot water, effective heating or cooling systems, and smoke detectors can also violate habitability standards. 

It’s crucial for homeowners looking to sell their properties to understand these factors, ensuring they address any issues that could impact the habitability and legal compliance of their home.

What Makes a House Uninhabitable in New York?

In practice, a house is uninhabitable when it fails on any one of these: no working heat, no running water or a failed cesspool or septic system, unsafe or absent electric, structural damage, fire or flood damage, serious mold, or a vacate order from the town. One is enough. On Long Island, the call is made by your town’s building or code enforcement department, not by the county or the state.
Homes on Long Island may become uninhabitable due to various critical issues:

  • Pest Infestations: Significant invasions by pests or rodents can compromise health and safety.

  • Electrical Hazards: Faulty electrical systems pose fire risks.

  • Structural Concerns: Damage affecting structural integrity, such as unsafe staircases or ceilings, can endanger residents.

  • Utility Failures: The absence of water, heating, cooling, or reliable electricity makes living conditions untenable.

  • Toxic Materials: The presence of asbestos, lead paint, or high carbon monoxide levels can seriously impact health.

  • Fire Risks: Lack of smoke detectors or unsafe wiring increases fire danger.

  • Mold and Water Damage: Untreated mold from moisture issues or water damage can lead to health problems and compromise a home’s structure.

  • Security Flaws: Inadequate security measures can also render a home unsuitable.  This could be anything from non-working exterior locks to too many personal belongings (hoarder house)

Understanding and addressing these issues is crucial for homeowners facing uninhabitable home challenges.

uninhabitable rental house on long island

What Happens When a House Is Deemed Uninhabitable?

When a Long Island home is declared uninhabitable, it initiates a series of challenges and decisions for homeowners and potential buyers. This status typically results from failing to meet basic living standards due to significant damage, safety hazards, or health risks.  These uninhabitable living conditions can typically be found in a rental house where the tenant or tenants have ignored issues that make it an unlivable house. Another common scenario that makes a property uninhabitable is when there is a house that has been abandoned for a long period of time such as in the case of a property going through probate.

The impact is multifaceted: homeowners may need to find temporary housing while resolving the issues, potentially affecting their ability to sell the property.  Addressing the impact of an uninhabitable home goes beyond just inconvenience; it fundamentally disrupts the lives of the resident or homeowner which then affects their ability to reside in or sell their property. When homes have these kinds of safety hazards or lack basic utilities it creates not only logistical but also financial and emotional burdens. This situation highlights the critical steps homeowners must take to rectify these conditions or possibly even sell the property. If selling becomes an option,  buyers might be deterred by the risks, demanding substantial discounts to account for repair costs. Legally, sellers must disclose the uninhabitable status of such houses, with failure to do so leading to possible legal actions. The valuation of a home that is deemed uninhabitable can significantly decrease because potential buyers have to account for the cost of necessary repairs and upgrades. This adjustment in market value often leads to prolonged listing periods and will almost certainly result in lower selling prices, posing a substantial challenge for homeowners looking to sell rental properties under these conditions. Nevertheless, specialized professionals can navigate the sale of such properties, offering a streamlined, worry-free process for homeowners facing this predicament. If a rental property has become uninhabitable, the local housing authority could get involved. A tenant may even begin withholding rent. If this happens, it is even more important to consider selling to a professional that is familiar with tenant’s rights and can make sure the situation is handled so as to avoid any legal action from the tenants.

Options For Dealing With an Uninhabitable Home on Long Island

Facing an uninhabitable home can be overwhelming, but actionable steps can mitigate the issue. Begin by assessing the damage or deficiencies to understand the scope of problems. Engaging professionals for inspections or repairs might be necessary. 

If the home is your primary residence, consider your living situation and whether temporary housing is needed. Look into insurance coverage or financial assistance for repairs. Legal advice could also be beneficial, especially regarding disclosures if selling the property. Lastly, exploring the market for selling options, including specialists in distressed properties, can provide a pathway forward.

Safety First

Ensuring tenant safety is paramount when a house is declared uninhabitable. If there’s any immediate danger to occupants, like compromised structural integrity or serious health hazards, vacating the property promptly is essential. Arranging for temporary accommodations becomes a priority, followed by a professional evaluation to assess and address the risks involved.

Address The Root Cause

Identifying the root cause of your home’s uninhabitability is critical. This often means engaging with professionals like building inspectors or contractors who can pinpoint issues such as structural damage or pest infestations. Understanding these underlying problems is the first step toward developing a comprehensive remediation plan.

After understanding the issues with your property, assess your options thoughtfully. The decision to repair or sell “as-is” hinges on the severity of the problems, available budget, and desired timeline. This step is crucial for setting a realistic course of action that aligns with your financial and personal goals.

Comparing Repairs vs Selling As-Is

For repairs, start by getting quotes from reputable contractors, focusing first on safety, plumbing, and essential utilities. It’s important to plan and budget carefully due to the potential costs and time involved.

Alternatively, if selling is your preferred route, look into companies or real estate investors in New York specializing in purchasing homes “as-is.” This option can offer a quick, hassle-free way to move past the challenges of an uninhabitable property without the burden of expensive repairs.

Can a Condemned House Be Sold in New York?

Yes. A condemnation order bars anyone from living in the house. It does not bar you from selling it. Ownership and occupancy are two different things in New York, and the deed can transfer while the vacate order sits on the property.

Here is what actually happens. When a town building department on Long Island condemns a house (in Hempstead, Babylon, Islip, Brookhaven, or any other town, it is the local code enforcement office that issues the order), the order and any open violations attach to the property, not to you personally. Whoever buys the house inherits the violations and the repair or demolition requirements that come with them.

That is why condemned houses almost never sell to traditional buyers. A lender will not write a mortgage on a house nobody is allowed to occupy, so financed offers are off the table. The realistic paths are: fix everything the town requires and then sell, which on a structurally compromised house can cost more than the repairs are worth, or sell as-is for cash to a buyer who takes on the violations, the vacate order, and the renovation.

We buy condemned and uninhabitable houses across Nassau and Suffolk exactly this way. We take the property as it sits, violations and all, and handle the town’s requirements after closing. And we will tell you straight if your house is close enough to compliant that fixing it first would net you more.

One honest warning: if the town has already moved toward demolition and placed the cost against the property, that becomes a lien that gets paid out of your proceeds at closing. Here is how that works: selling a house with a lien in New York. Talk to your attorney before accepting any offer in that situation.

selling unlivable property on long island

The Realities of Selling an Uninhabitable House on Long Island

Selling a home deemed uninhabitable poses unique challenges, significantly narrowing the pool of potential buyers primarily interested in move-in ready homes. If you are a landlord, the amount of repairs in an uninhabitable rental property and the overall condition can drastically reduce its market value, leading to potential financial losses.

Sellers must navigate legal obligations to disclose the property’s state, further complicating the sales process. Financing hurdles for buyers, due to lenders’ reluctance towards homes failing to meet livability standards, and the extended time such properties spend on the market, exacerbate the difficulties for sellers, increasing both frustration and financial strain.

Selling an uninhabitable property entails strict legal and ethical responsibilities for sellers to disclose all known defects, including the uninhabitable status. Neglecting this duty can lead to serious legal consequences and possible lawsuits from uninformed buyers.

Attempting to finance the purchase of an uninhabitable home can be challenging for buyers, as lenders typically shy away from properties that don’t meet basic livability criteria. This hesitance further narrows the buyer pool. 

Additionally, the longer a property remains unsold on the market due to its condition, the more likely sellers are to face increased frustration and financial burden from prolonged carrying costs.

We Buy Long Island Homes Fast: Experience and Compassion with Fast Action

We Buy Long Island Homes Fast provides an effective solution for homeowners dealing with the complexities of selling an uninhabitable property. Regardless of the extent of repairs needed or structural issues present, We Buy Long Island Homes Fast ensures a seamless and expedient selling process for houses in any condition, offering peace of mind and a hassle-free experience for sellers anywhere located on Long Island.

Working with We Buy Long Island Homes Fast simplifies the selling process for homeowners, eliminating the stress and complexity of traditional real estate transactions. This approach bypasses the need for repairs, lengthy negotiations, and multiple house showings, offering a more straightforward and hassle-free experience.

We Buy Long Island Homes Fast simplifies the sales process by directly purchasing homes from owners, eliminating the need for traditional market listings. This method provides a straightforward option for cash sales, especially appealing in regions like Long Island where homeowners seek prompt, reliable transactions for properties that may require significant work.

Choosing We Buy Long Island Homes Fast for selling an uninhabitable house offers homeowners a fast, hassle-free selling experience. Key benefits include a direct purchase process eliminating market listings, avoiding the stress of repairs and showings, and ensuring a quick, reliable cash transaction. This streamlined approach provides a unique solution for owners facing the challenges of selling properties in less-than-ideal conditions, offering peace of mind and financial relief.

getting cash for a long island home that is unlivable

Conclusion

Selling an uninhabitable home presents unique challenges, yet We Buy Long Island Homes Fast offers a comprehensive solution that simplifies this process significantly. From eliminating the need for repairs and bypassing traditional market listings to providing a stress-free, direct cash transaction, this service transforms what could be a daunting task into a manageable and efficient sale. 

Homeowners benefit from a streamlined approach that removes the hurdles of conventional real estate sales, ensuring a quick and satisfactory resolution to selling properties in less-than-perfect condition. This service not only accelerates the selling process but also offers peace of mind, highlighting a tailored solution for homeowners on Long Island facing the complexities of selling uninhabitable properties.

Finding the Right House Flipper Near You: A Long Island Homeowner’s Guide

Finding the Right House Flipper Near You: A Long Island Homeowner's Guide

Are you looking for a house flipper near you because you might want to sell your Long Island home? If you have a property you wish to get off your hands, you don’t want to mess around. You want the process to be quick and efficient, but most importantly, you want to maximize your return on investment.

Long Island real estate is in huge demand. The median sales price for a property in this affluent metropolitan area of New York is around $800,000, a figure that increases year upon year. Long Island is incredibly attractive to both potential homeowners and real estate investors for its suburban serenity and access to major urban areas.

So if you live on Long Island and are looking to move to a new location, downsize, or upgrade to a bigger property, you know it won’t be long before an investor or potential homeowner comes knocking. But we all know that moving house is one of the most stressful experiences you can have in life. It takes a great deal of time and effort to make it happen. You have to clean and prepare the home to go on the market, deal with any needed repairs, and fill out a wealth of paperwork and legal paraphernalia before your house is even listed. And finding buyers or investors to take it off your hands can take even longer.

This is why house flipping can be an incredibly beneficial path to go down. Selling to a house flipper offers the most convenient solution to selling your home and making a profit at the same time. The following article explores the complex world of house flipping to help you understand all the facts and potential risks of this real estate strategy and decide whether or not it is the right choice for you.

Read on to learn more.

finding a house flipper near you

Understanding the Role of House Flippers

So what is house flipping?

House flippers are essentially real estate investors or companies who buy properties to sell them for a profit. Typically, a house flipper is likely to buy these homes below market value, and will often focus on houses that are in need of repairs or renovations. They will then perform substantial work on the property to ensure it is in peak condition before selling it for a significant profit.

Although it may sound simple and straightforward, house flippers are shrewd investors who have in-depth knowledge of market trends, renovations, contract law, costs, sales price, home equity lines, and other important concepts. Sellers typically do their due diligence when doing deals with potential buyers, and a house flipper typically purchases properties with complete confidence that they will make money on the sale and benefit from this great source of income.

But behind the scenes, flipping a house is rarely a leap of faith—it’s a calculated move. Before making a purchase, experienced flippers ask plenty of questions to uncover every detail that could affect their investment. They investigate the current market value of the neighborhood, evaluate any legal issues or local ordinances that could slow down a sale, and dig into the property’s history to spot red flags.


Scouting reliable contractors for renovations is another crucial step. Flippers often research and vet their teams in advance, knowing that the quality and speed of the rehab work can make or break a deal. Reviewing paperwork carefully—whether purchase contracts or permits for renovations—helps them avoid costly surprises down the road. This thorough approach allows house flippers to assess risks, make confident decisions, and set themselves up for a profitable outcome.

This easy sales process stands in contrast to using typical real estate agents. And for both the homeowner and the real estate investor, there are mutual benefits when it comes to flipping houses. Here are some of the advantages of the house flip process.

Benefits for Homeowners

  • Convenience

    A major worry for the average seller is that the transfer of ownership will take a huge amount of time and energy. When making a flipper sale, however, everything happens a lot more quickly. When flipping houses, the sales process will not require as many inspections, and the investor will be less interested in ensuring renovations or repairs have been made before they purchase the property. The house will be sold in less time than a traditional real estate agent.

    This speed is a hallmark of working with house flippers. These transactions tend to move rapidly, so potential sellers (and buyers) should be ready for a streamlined process. Flippers typically aren’t interested in drawn-out negotiations or waiting for buyers to line up pre-qualifications—they want to move fast and close the deal. Because of this, it’s important to be prepared before entering into a flipper sale: have all necessary paperwork and finances in order, and be clear on your contingencies in case anything unexpected arises. Being organized and decisive can help you take full advantage of the convenience and efficiency that flipper sales offer.

  • No Repairs: When going down the traditional sale route, you have to spend a lot of cash to fix your home up before it goes on the market. Home’s after repair can sell for full value on the market if you are using a real estate agent. But when you decide to flip houses, investors will purchase your property without you needing to pay repair costs. This way, they get better deals as the home is sold under market value, and you can get it off your hands quicker. The profit might be smaller, but you have saved money on labor.
  • Flexibility: Often, when transferring ownership of a property, you are at the mercy of the real estate agent and subject to bank appraisals. But if you choose to flip houses, you can often pick your own closing date and ensure the house is sold on your own timeline.

Benefits For Flippers

  • Profit: Flipping houses gives investors access to incredible deals on property, as they will be buying houses from sellers below typical market price. When they make repairs and flip these assets later on, they stand to make an enormous profit and it is a very lucrative business. In addition, there are minimal start-up costs, and they only need the initial capital to purchase real estate at a reduced price. It is worth sellers understanding and bearing it in mind when you are undergoing negotiations.
  • Flexible Working: House flippers can work from anywhere, at any time. It is a great business to operate, as it gives investors complete freedom and flexibility over their lives. It can be a primary source of income, or a side hustle to make a little extra cash. There are all kinds of flippers out there, so it’s important to know who you are doing business with and how they operate.
  • Choice: As long as the flipper is knowledgeable about the real estate market, there is huge potential for making money and so many different options out there. The choice of properties, sellers, and neighborhoods is endless.

Potential Risks for the Property Seller

To determine whether or not to sell to a house flip investor, it’s a good idea to understand the risks as well as the rewards. For example, there is the potential for a lower sale price. You effectively pay for the convenience, and the investor will purchase your property for a lower price so they can flip it to maximize return on investment.

As with any business, there is always the potential for scams. You should do your research before parting with your money and ensure that any business or investors you deal with are reputable and above board. If you meet with a flipper and feel they are untrustworthy or that something isn’t right, remember that you can always walk away and seek out another opportunity. There are plenty of flippers out there who are highly regarded and credible within their industry. Make sure you look after yourself and your money.

Alternatives to Selling to a House Flipper

If you decide that the house flipping route isn’t quite right for you, don’t worry—you still have plenty of options. Some homeowners choose to sell their properties the traditional way by listing with a licensed real estate agent, which can help you attract a wider pool of buyers and potentially secure a higher sale price (though you may have to invest more time and effort in repairs and showings).

Another possibility is working with iBuyer companies such as Opendoor, RedfinNow, or Zillow Offers, which provide instant cash offers on homes and allow for quick closings. While these services sometimes offer less than full market value, they’re generally reputable and can be an option if speed and convenience are your priority.

You could also consider selling your home directly to someone you know—perhaps a relative, friend, or trusted acquaintance. This approach might allow for more flexible terms, personalized negotiation, and a smoother transition.

The bottom line: Whether you partner with a real estate agent, an iBuyer, or you choose a private sale, it’s important to weigh your options and pick the route that best fits your timeline, goals, and comfort level.

house flippers on long island

Finding House Flippers

So once you have decided to sell to a home flipper, how do you find them? There are plenty of flippers out there, whether it’s an investor or a business, who are looking to flip properties on Long Island. But you need to find a quality investor who will help you make some extra cash from your property.

The best method is to use an online search engine such as Google. Putting search terms like “find house flippers near me” or “Long Island House Flippers” is the best way to find willing investors in your area. You will want to choose a local home flipper, as they will have an understanding of the market price of houses in your neighborhood.

If you find yourself facing financial difficulties or simply want to move on quickly, selling to a house flipper can be a lifeline.

Using Online Real Estate Resources to Spot Local Flip Opportunities

Online real estate platforms like Zillow, Realtor.com, and Redfin are powerful tools for anyone interested in tracking down properties currently undergoing flips in their neighborhood. These websites allow you to search for homes listed as recently renovated, price-reduced, or even marked specifically as “investment potential”—all of which are telltale signs of a flip.

Here’s how they come in handy:

  • Identifying Flip Hotspots: By browsing listings in your area, you can easily spot neighborhoods where renovated homes are popping up for sale. This insight helps both sellers and potential investors understand where flipping activity is concentrated.
  • Comparing Listings: Use filters to look at recently updated properties and compare prices across multiple homes. This gives you a sense of which flips are fetching top dollar and which deals stand out.
  • Market Research: Many of these sites provide historical sale data, property tax records, and renovation details, so you can gauge whether a flip has been handled well or is worth a second look.

By learning how to leverage these platforms, you position yourself to either connect with local flippers or better understand current market conditions. This way, when you’re ready to make your move—whether selling or investing—you have real-time data to guide your decision.

Evaluating Potential Flippers

Any seller needs to ensure the buyer is trustworthy before making a deal.

Read reviews of local house flippers online to make sure there are no red flags and that they are above board. Ideally, there will be plenty of testimonials from satisfying customers, rather than a wave of one-star reviews. Watch out for potential scammers and be proactive when deciding whether or not you should part with your money.

You can even ask for references or proof that they are licensed in the real estate space. You will want to have some evidence that the home investor actually buys, renovates, and sells properties on the real estate market. It can be useful to understand where the investor is getting their money from. For example, are they financing through hard money lenders or another source? A hard money lender enables an individual to buy an investment property even if they don’t have good credit so consider this before transferring ownership.

Preparing Your Home for Sale

As we have seen, one of the great advantages of selling to a company that flips houses is that you are not required to make huge repairs and changes to your house before selling. Since these investors purchase houses so they can make improvements and then re-sell, they almost always buy your home as it is.

Of course, those who flip houses will not just buy any property, and you want to do what you can to make your home more appealing to flippers. They need to be able to see that they can make a return on investment and get a good deal for their cash.

Although massive renovation work and extensive deep cleaning may not be necessary, a quality house flipper may still have standards they work to and will not make an investment if these are not met. Make sure you discuss which changes, if any, your flipper will want to see. Most will allow you to sell as-is without making repairs or cleaning. However, if there are extensive structural problems or other major issues, some could be reluctant.  On the other hand, there are those that will buy houses in need of major repairs without hesitation.  That’s why you should research house flippers near you to see which one will meet your needs.

As long as you have open, transparent, and honest communication with your flipper, you can ensure that both parties are happy with their investment, and everyone gets exactly what they want from the deal.

selling home on long island to a company that flips houses

How Can I Find Long Island House Flippers Near Me?

So to summarize, finding a local Long Island house flipper or house flipping company is a great way to sell your property for a profit while ensuring you can complete the process as quickly and efficiently as possible. You want to make sure you find a local flipper with knowledge of the real estate market, and a trustworthy, reputable background.

Finding a flipper is a journey of mutual discovery, with benefits on both sides of the table. Be sure to approach the process with openness, and a mindset towards finding the best match for your needs. Be patient and thorough in your search, and you will sell your home as conveniently as you can.

For more information and advice on finding the right house flipper near you, get in touch to learn more. Or if you are ready to sell your home now, we can give you a fair offer on your property.

Good luck selling your home and starting your new life!

What Repairs Are Required for an Appraisal?

What Repairs Are Required for an Appraisal?

Have you been hoping to make a fast house sale in NY quickly, only to discover you need to spend thousands on repairs?

The fact is that appraisals can halt a home sale. Right when you thought you were ready to list, the appraisal complicates things.

Now, you must invest in more property fixes or risk losing the deal.

But what if you could sell your house as-is on Long Island to cash home buyers without the burden of home appraisal repair requirements? Read on to learn about an alternative for homeowners who need to sell fast.

what repairs for home appraisal

What Repairs Do Appraisers Look For?

When examining a home, appraisers are meticulous. They look for issues that may affect safety, livability, and structural integrity as required by FHA appraisal guidelines in NY.

Structural Integrity Problems

Appraisers will flag any structural issues like cracks in foundations or walls, water damage, evidence of termites, or other pests that undermine the home’s physical stability.

Even small cracks can hint at larger issues underneath that need professional assessment and repair.

Safety Hazards

During an appraisal, the appraiser will flag faulty railings, damaged steps, exposed electricity, fire hazards, and anything that presents a safety risk to occupants.

Safety issues can make it challenging for lenders to insure the property.

Roof Condition

One of the most expensive inspection points is the roof.

Appraisers will assess the roof’s age, material condition, and drainage and look for any evidence of leaks or damage. A full replacement is often required if the roof is near or past its expected lifespan.

Plumbing Functionality

Appraisers test water pressure at all fixtures and check for any leaks showing pipes need repair.

Appraisers flag any signs of faulty plumbing appliances, poor drainage, or outdated fixtures to meet financing standards.

HVAC Issues

Lenders require properties to have adequate systems for climate control and comfort. Faulty heating or cooling, improperly sized AC units, and outdated furnaces may need replacement to ensure the home is comfortable and efficient.

Outdated Electrical, Insulation, and More

Homeowners must address any home systems that appear outdated, insufficiently grounded, or hazardous.

Insulation that allows energy leaks, knob and tube wiring, or inadequate amperage for modern devices are common electrical issues requiring upgrades.

Lead Paint and Asbestos Repairs

In addition to the standard appraisal requirements, older homes in NY must follow strict regulations regarding lead paint and asbestos.

New York is known for its historic homes, but these properties often have layers of old paint or insulation containing lead and asbestos.

Both materials can pose health risks if disturbed, making it essential to follow proper procedures when handling them.

home appraisal repairs

Why Appraisal Repairs Are a Pain for Sellers

Coming up with cash to make appraisal repairs is difficult when you’re trying to sell. Even minor fixes can add up fast, cutting a chunk out of your return on investment.

And there’s no guarantee your repairs will translate to a higher appraisal.

Lenders sometimes impose the strictest requirements, forcing home improvement repairs that go beyond what safety requires.

And because appraisal services are subjective, different appraisers will flag different issues.

If repairs are not made, the lender can refuse sale financing based on a low appraisal. Deals frequently crumble at the last minute due to appraisals, despite the investment of time, money, and emotions.

This presents sellers with a tough choice: roll the dice and hope the appraisal comes in favorably or pour money into a home you’re about to sell.

Your Appraisal Repair Dilemma-and the Simple Solution

Like many Long Island homeowners, you’re probably facing this appraisal repair dilemma. You’re faced with a few options.

Option One: Make the Repairs

You could invest money into making all the repairs the appraiser demands and the buyer’s lender requires. There’s no guarantee repairs will increase the appraised value enough to be worthwhile.

Despite spending thousands on renovations, the appraisal may still come in low. Then you’re out of money and time, with a sale at risk, anyway.

Option Two: Avoid Appraisal Repairs

You have the option to sell as-is in hopes of a good enough appraisal. But then you risk the buyer’s lender denying financing because the appraisal flags issues that need to be fixed.

A no-repair home sale may fall through despite everything because nobody has dealt with the issues.

Option Three: Sell to a Cash Buyer

The smarter choice is to sell your home to a cash buyer like We Buy Long Island Homes Fast. We purchase properties in their current condition; no repairs or appraisals are needed.

You get a fair cash offer upfront, close on your own timeline, and avoid the financial pitfalls and uncertainty of the appraisal process. It’s the most seamless, efficient way to sell fast and move on.

avoiding lender required repairs

Why Cash Home Buyers Are the Smarter Choice

Selling your home can be a long, complex process filled with potential setbacks, especially when dealing with appraisals and repairs. Selling to a cash buyer streamlines this process by eliminating these obstacles.

Selling to a cash buyer has many unique advantages:

  • No appraisals or lender requirements to meet
  • No negotiating over which repairs are mandatory
  • No delaying closing date because of renovation timelines
  • No risk of losing equity by making unwise repairs

As experienced Long Island cash home buyers, we buy properties as-is without requiring repairs or bank appraisals.

If you need to sell your Long Island home fast, avoid unpredictable appraisal repairs, and walk away with cash in hand, contact us today!

We make fair cash offers based on a home’s current condition. No property fixes or upgrades are necessary!

And because there’s no mortgage, we can close much faster within your timeline.

It takes the uncertainty, stress, and financial pitfalls out of the home-selling process.

Sell Without Home Appraisal Repair Requirements

Direct home buyers are an excellent option if you need to sell your Long Island home fast.

Our quick-closing real estate process is a predictable cash sale. You can avoid the home appraisal repair requirements, negotiations, and uncertainty of a traditional sale.

If you need to sell your house on your own terms, contact We Buy Long Island Homes Fast for a no-obligation cash offer.

Don’t let appraisals stand in the way of your real estate goals. Contact us to make selling your Long Island home a stress-free experience!

Who Can Put a Lien on Your House in New York?

Many homeowners have mortgages on their homes, and a mortgage is a lien. There are many types of liens, but mortgage loans are the most common.

A lien gives someone financial claims to a house. While liens are common, they can also complicate a home sale. 

You must repay the liens when you sell a house with a lien in NY. Have you ever wondered who can put liens on properties and why people do this? Are you wondering how liens affect a home sale?

Continue reading this guide to learn about liens on homes in New York.

who can put a lien on a house in new york

What Is a Lien on a House?

A lien is a legal claim against your house that a person or organization can file when you owe them money. It attaches to the property itself, not only to you, so it usually has to be paid off or resolved before you can sell the home with clear title. The most common lien is a mortgage, but unpaid property taxes, an unpaid contractor bill (a mechanic’s lien), and court judgments can all create liens too.

Types of Liens in New York

Mortgage liens are common. When you buy a house with a loan, the lender places a lien on the house. This lien gives the lender rights to your home if you fail to pay the mortgage.

The lender can order a foreclosure and keep the money you owe on your mortgage. The lender also requires repayment if you sell the loan. The lien amount changes as you pay down your mortgage balance. 

Here are some other types of liens you may have on your New York property:

Mortgage Liens

The most common lien of all, and a voluntary one: you agreed to it when you borrowed. The lender holds a lien on the house until the loan is paid. At payoff, the lender records a satisfaction of mortgage so the record shows the lien is gone. Most Long Island homes carry one, and it is not a problem, it is just how home loans work.

Tax Liens

Tax entities can place liens on your house if you fail to pay the taxes you owe. For example, your county or state may place a lien on your house if you have overdue property taxes

The Federal government may place a lien on your house if you owe tax money. 

Mechanic's Liens

Building contractors can also use liens when you owe money. They use mechanic’s liens to place a financial claim on a home.

For example, suppose you hire a contractor to remodel your kitchen. If you owe the contractor money and won’t pay, they can place a mechanic’s lien on your house.

Like all liens, this one requires repayment if you sell your house.

Judgment Liens

judgment lien is another type someone may place on your home. A creditor can place this on your home if a court rules against you in a case. The court must create a judgment for the creditor to file a lien.

Do liens expire? Judgment liens expire 10 years after someone places them on a property. However, a creditor may have the legal right to renew it. 

Federal Tax Liens (IRS)

A homeowners association, condo board, or co-op can place a lien for unpaid common charges or assessments. On Long Island these show up most in condo and HOA communities in places like Holbrook, Coram, and Port Jefferson. Left unpaid, an HOA lien can grow with interest and legal fees, and in some cases the association can push toward foreclosure.

Medicaid Liens

New York can place a lien on the home of certain Medicaid recipients to recover care costs, usually in nursing-home situations. The rules have important exceptions (a spouse or certain family members living in the home can block or delay recovery). If one of these appears in a title search, this is an elder-law attorney conversation, not a DIY project.

Judgment Liens

When federal taxes go unpaid, the IRS can file a Notice of Federal Tax Lien that attaches to everything you own, including your house. Federal liens have their own removal process with real lead times, so they deserve early attention rather than last-minute scrambling.

how can i remove a lien in new york

How Long Does a Lien Stay on Your House in New York?

It depends on the lien, and “old” does not automatically mean “dead.”

A judgment lien on New York real property runs ten years from the judgment-roll filing and can be extended for another ten (CPLR 5203). The underlying debt is presumed paid only after twenty years (CPLR 211(b)), so a judgment from years ago can still be very much alive.

A mortgage lien lasts until the loan is paid, and then the satisfaction gets recorded (RPL 321). Property tax liens do not age out; they sit until paid and, left long enough, they start the county’s enforcement clock. Federal tax liens generally follow the IRS collection window, which runs about ten years but can be extended in some situations.

The honest takeaway: never assume a lien has expired. Pull the record at the county clerk, or have your attorney do it, and read the actual dates.

How Long Does a Lien Stay on Your House in New York?

There are five real paths, and which one applies depends on the lien and whether it is legitimate.

Pay it and record the release. The direct route: pay the debt, then make sure the creditor records a satisfaction or discharge. Do not skip the recording step; an unpaid-looking record causes problems years later.

Dispute it. Liens can be defective: wrong amount, wrong property, missed deadlines, or work that was never done as claimed. A contractor’s lien in particular has strict filing rules, and your attorney can challenge one that does not comply.

Bond it off. For a mechanic’s lien, New York lets you substitute a bond at 110 percent of the lien amount (Lien Law 19), which frees the house while the dispute continues against the bond instead.

Negotiate it down. Creditors with old judgments often settle for less than face value in exchange for actually getting paid and releasing the lien. Everything in writing, always.

Let it expire, carefully. Some liens do lapse, but as covered above, extensions and long debt presumptions make this the riskiest strategy. Verify with counsel before you count on a calendar.

If the reason you are dealing with the lien is that you want to sell the house, the removal usually happens AT the closing out of your proceeds, which is a different and often easier path: here is exactly how selling a house with a lien works in New York.

selling a house with a lien in new york

Frequently Asked Questions

Who can put a lien on your house in New York?

The county or state for unpaid property taxes, the IRS for federal taxes, a lender through your mortgage, contractors who worked on the house, creditors who win a court judgment, and an HOA or condo board for unpaid charges. Nobody can slap a lien on your house just by claiming you owe them; each type has its own legal filing process.

How do I find out if there is a lien on my house?

Search the public record at the county clerk: Nassau County Clerk records for Nassau, Suffolk County Clerk records for Suffolk, both searchable online by name. A title company or your attorney can run a full search that catches everything, which is exactly what happens automatically when you sell.

How long does a lien stay on your house?

Judgment liens run ten years and can be extended; mortgages last until paid; property tax liens sit until resolved; federal tax liens generally follow the IRS ten-year collection window. Old does not mean gone. Check the record before assuming anything.

If You Are Selling a House With a Lien

Liens complicate a sale, but they do not stop one. You can still sell, and each lien type clears its own way: paid off, released, bonded, or discharged at or before closing. We wrote a complete plain-English guide with every step, the Nassau and Suffolk specifics, and the primary sources: selling a house with a lien in New York.

If you want to skip the process entirely, we buy Long Island houses with liens for cash, as-is, and our title company handles the clearance. Before you hand a lien-heavy house to any cash buyer, confirm they are the real thing: here is how to tell whether a we buy houses company is a ripoff.

The full sale mechanics, lien by lien, are here: Can You Sell a House With a Lien on It in New York?